Author: mdimdadulhaq10@gmail.com

  • Freelancer Month-End: Match Card Charges in 15 Minutes

    Freelancer Month-End: Match Card Charges in 15 Minutes

    Example scenario: a freelance designer sits down in March to prepare last year’s numbers for her accountant. Her one card paid for groceries, Adobe, a font license for a client, three AI tools, stock photos billed back to two clients, and a flight to a workshop. She spends a full weekend digging through email for receipts, and still cannot remember which stock photo charges she already rebilled.

    Most freelancers do not need more accounting software. They need a short monthly habit and a card setup that does half of the sorting automatically. This guide gives you a 15-minute month-end routine for matching card charges to receipts and invoices, a tagging scheme your accountant will thank you for, and a simple way to split charges by type so most lines are already categorized before you start.

    Why card charges are hard to match

    • Mixed spending. Personal and business charges share one statement.
    • Vague merchant names. The statement shows a payment processor name or abbreviation, not the product.
    • Receipts live in many inboxes. Some arrive by email, some sit in vendor dashboards, some never arrive.
    • Rebillable costs. Expenses you pass on to clients need to be tracked until they appear on an invoice.
    • Foreign currency. The amount on the receipt differs from the amount on the statement after conversion.

    Good records matter beyond tidiness. As the IRS recordkeeping guidance for small businesses notes, you must be able to support the entries and deductions on your return, and you can use any system that clearly shows income and expenses. Rules differ by country, so check with your own accountant or tax office.

    Set up once: three things before the first month-end

    1. A receipts folder. One cloud folder with a subfolder per month. Forward or save every business receipt there the day it arrives.
    2. A short list of expense tags. Six to eight is enough. See the table below.
    3. Separate cards by expense type. At minimum, keep business and personal apart. Better: one card for recurring software, one for client-rebillable costs, and one for everything else in the business.

    Suggested expense tags

    TagExamplesTypical card
    Software and subscriptionsDesign suite, AI tools, cloud storageSubscriptions card
    Client rebillableStock images, fonts, licenses bought for a clientRebillable card
    MarketingPortfolio hosting, ads, domainGeneral business card
    EquipmentMonitor, drawing tabletGeneral business card
    TrainingCourses, books, workshopsGeneral business card
    TravelFlights and hotels for client workGeneral business card
    Personal (exclude)Anything not for the businessPersonal card only

    The 15-minute month-end routine

    Do this on the first working day of each month. Set a timer.

    1. Minutes 0 to 2: Export statements. Download last month’s transactions for each business card as a spreadsheet.
    2. Minutes 2 to 6: Match the subscriptions card. These charges repeat, so most lines match last month’s receipts. Tick each one and save any missing receipts from the vendor’s billing page.
    3. Minutes 6 to 9: Match the rebillable card. For each charge, write the client name and whether it is already on an invoice. Anything not yet invoiced goes on the next invoice draft now.
    4. Minutes 9 to 13: Match the general business card. Tag each line and pair it with a receipt from the month’s folder.
    5. Minutes 13 to 15: Log exceptions. Note any charge with no receipt, any refund, and any currency difference. Send the file to your bookkeeper or save it for tax time.

    The routine fits in 15 minutes only because the cards did the first round of sorting. On a single mixed card, step 2 to step 4 merge into one long hunt.

    Quarterly and yearly add-ons

    The monthly routine keeps records current. A few extra checks at longer intervals keep them useful.

    Every quarter (about 30 minutes)

    • Total each tag for the quarter and compare it with the previous quarter. A jump in software spend is often a forgotten trial.
    • Check that every rebillable charge has been invoiced and paid.
    • Cancel subscriptions you did not use in the last three months.
    • Set aside money for tax payments if your country uses quarterly estimates.

    Once a year (about an hour)

    • Combine the twelve monthly sheets into one file for your accountant.
    • List equipment purchases separately, since they may be treated differently from running costs.
    • Review your tag list and merge or add tags based on how your work has changed.
    • Archive the receipts folder according to the retention period your accountant recommends.

    Template: monthly matching sheet

    DateCardMerchant (as shown)Amount chargedReceipt amount and currencyTagClient (if rebillable)Invoiced?Receipt saved?
    3rdSubscriptionsDesign suiteFill inFill inSoftwaren/an/aYes
    11thRebillableStock image siteFill inFill inClient rebillableClient AInvoice 0142Yes

    One card versus separate cards per expense type

    FactorOne card for everythingSeparate cards by type
    Month-end timeLong and unpredictableShort and repeatable
    Rebillable trackingEasy to miss itemsEvery line on one card is rebillable
    Personal charges in business recordsCommonRare
    Effect of a compromised cardEverything stopsOnly one expense type is affected
    SetupNoneOne-time

    Example: expense-type cards with Vizovcc

    If your bank will not give you several business cards, prepaid virtual cards are one alternative. Vizovcc sells prepaid virtual Visa and Mastercard cards that you buy from one account balance funded with crypto such as USDT, USDC, Bitcoin or ETH. You can hold several cards in one account, each with its own balance, and freeze or unfreeze any of them from the dashboard. Signing up needs an email, and there is no credit line or monthly bill to pay off.

    A freelancer could use one Vizovcc card for software and subscriptions and another for client-rebillable purchases. The fixed balance on each card works as a budget: if the rebillable card runs low, it is a reminder to invoice those clients. Freezing the subscriptions card for a month you are not working stops renewals from going through. For how the cards themselves work, see Vizovcc’s guide to virtual Visa and Mastercard cards for subscriptions and software.

    Some practical notes. Each merchant decides which cards it accepts, and some decline prepaid cards, so try a card on a smaller subscription first. Card purchases are final, so choose a card size you will use. Prepaid card statements are another record to keep, so download card transactions each month alongside your bank exports.

    FAQ

    What if a receipt is missing?

    Check the vendor’s billing or account page first; most SaaS tools keep invoices there. If you still cannot find one, note the charge details and the business reason in the exceptions column and ask your accountant how to treat it.

    How do I handle currency differences?

    Record both amounts: the receipt amount in its currency and the amount charged to your card. Your accountant can then apply whichever rate your local rules require.

    Do I need accounting software for this?

    Not to start. A spreadsheet and a receipts folder work well. If you later adopt software, the tags and card split carry over directly.

    Key takeaways

    • Month-end takes 15 minutes when cards are split by expense type before you start.
    • Save receipts into one monthly folder as they arrive, not at tax time.
    • A dedicated rebillable card makes it hard to forget charges you owe clients an invoice for.
    • Keep personal spending off business cards entirely.
    • Check your local record rules with an accountant; the routine supports them, it does not replace them.

    Set a recurring calendar event for the first working day of next month and try the routine once. If you need extra cards to split expenses by type, Vizovcc is one prepaid option to compare with what your bank offers.

  • Family Subscriptions Without Sharing Your Main Bank Card

    Example scenario: your teenager needs to update the payment details on the family streaming account because the old card expired. You read your debit card number out over the phone while they type it in. A month later, the same card turns up as the payment method on a game account, a music upgrade and an in-app purchase you didn’t approve. Nobody meant any harm. The card was simply in the household now, saved on devices you don’t control.

    Family plans save money, but they create a payment problem: one card ends up paying for services that several people use and manage. This guide shows a safer family subscription payment setup, explains how Apple and Google family billing works, and covers how to keep your main bank card out of shared accounts entirely.

    Why sharing your main card is risky

    • It spreads across devices. Once a card is entered on a child’s phone or a shared tablet, it can be saved in browsers, apps and stores you don’t see.
    • Purchases are hard to trace. When everything is on one card, working out who bought what means questioning the whole household.
    • Expiry breaks everything at once. When the main card is replaced, every family service fails until someone updates it.
    • A breach hits your main account. If any family service leaks the card, it is your checking account that is exposed.
    • Kids can spend without meaning to. In-app purchases are designed to be easy, and a saved card makes them easier.

    How app store family billing works

    Apple Family Sharing

    In Apple’s Family Sharing, the family organizer usually pays. According to Apple’s guide to Purchase Sharing in Family Sharing, when Purchase Sharing is on, the organizer pays for family members’ purchases unless other adults use their own payment method. A purchase is charged first to the member’s Apple Account balance, with any remainder going to the organizer. Ask to Buy lets the organizer or a parent or guardian approve or decline a child’s purchase requests from their own device.

    Google Play family payment method

    Google lets the family manager add a family payment method that members can use for Google Play purchases. Google’s help center says the family payment method must be a credit or debit card, and the manager can choose which purchases need approval, from all content to none. Check whether the card you plan to use is accepted before relying on it.

    Streaming and other services

    Most streaming, music and storage family plans are billed to one account holder’s card. Everyone else joins through an invitation or profile. The account holder controls the payment method, so that is the person whose card choice matters.

    Family payment setups compared

    SetupControlRisk to main accountTrackingBest for
    Main bank card on every family serviceLow once sharedHighMixed with all household spendingNobody, ideally
    App store family billing with approvals onHigh for app store purchasesMedium, card still on file with the storePurchase list in the storeFamilies with young children
    Each adult pays their own subscriptionsEach adult controls their ownSpread across cardsHard to see the household totalAdult roommates or older teens
    One dedicated household subscription cardHigh: the balance is the budgetLow, separate from main accountOne clean listFamilies who want a clear subscription budget

    A safer family subscription setup, step by step

    1. List every family subscription. Streaming, music, cloud storage, games, learning apps and app store subscriptions. Note who uses each and who holds the account.
    2. Choose one account holder per service. Usually a parent. That person controls the payment method and the password.
    3. Turn on approvals for children. Use Ask to Buy on Apple or purchase approvals on Google Play so children request rather than buy.
    4. Move family services to one dedicated card. Replace your main card on each service with a separate card used only for family subscriptions.
    5. Remove your main card from shared devices. Check browser saved payments, app stores and game platforms on each child’s device.
    6. Set a monthly family subscription budget. Add up the plans from step one, add a buffer for tax and price changes, and fund the household card to that amount.
    7. Review together every quarter. Ask each family member which services they still use. Cancel the rest.

    Teaching kids about subscriptions

    A household subscription card is also a useful teaching tool. Show older children the list of services and the monthly total. Let them propose a new service and suggest which existing one to drop to pay for it. When the card balance is the family budget, the trade-offs become concrete rather than abstract.

    • Explain that “free” games often make money from in-app purchases.
    • Agree on a rule: no card details entered on any device without a parent.
    • Teach them to spot fake “your payment failed” messages that ask for card details.

    A dedicated prepaid card for family services

    A prepaid card works well as the household card because it can only spend what you load onto it. If a child signs up for something unexpected, or a family service leaks payment data, the most that can be charged is the card’s remaining balance, and your main account stays out of it.

    Vizovcc is one provider of this kind of card. It sells prepaid virtual cards bought with crypto from an account balance, each with a fixed loaded amount and nothing to repay. From the Vizovcc dashboard a parent can keep several cards on one account, for example one for streaming and music and another for games, see each card’s balance and freeze a card if an unexpected charge appears. Cards support 3D Secure, and card pages show Apple Pay and Google Pay compatibility. For how buying and using a card works, see this overview of prepaid virtual Visa and Mastercard cards.

    Be aware of the limits. Vizovcc does not offer spending limits you set per card, merchant locks, team roles or separate logins for family members, so keep the account login with a parent and give children access only through each service’s own family features. Each service decides whether it accepts prepaid cards, and Google’s family payment method has its own card requirements, so test with one service first. Card purchases are final.

    Frequently asked questions

    Should my teenager have their own card for subscriptions?

    For older teens, a card with a small, fixed balance can teach budgeting. Keep approvals on in the app stores until you are comfortable.

    Can I use a prepaid card for Apple Family Sharing?

    Apple uses the organizer’s payment method on file. Whether a particular prepaid card is accepted depends on Apple and the card, so try adding it and check that a purchase goes through.

    What happens if the household card runs out?

    Renewals on that card will be declined, and services may pause. Check the balance before the main renewal dates each month.

    Is sharing a streaming password the same as a family plan?

    No. Many services limit sharing to people in the same household. Follow each service’s terms for who can use a family plan.

    Key takeaways

    • Sharing your main bank card with the household spreads it across devices you don’t control.
    • Apple and Google family billing let one adult pay and approve children’s purchases.
    • One account holder per service keeps payment and passwords under control.
    • A dedicated household card turns the family’s subscriptions into one list and one budget.
    • A prepaid household card limits what unexpected charges or a breach can take.

    Sit down with your family this week and list every service you share. If you decide a separate household card makes sense, take a look at Vizovcc and choose a card whose balance covers a month of family subscriptions with some room to spare

  • Keep Your Main Bank Card Out of Online Checkout Forms

    Keep Your Main Bank Card Out of Online Checkout Forms

    Try this exercise, or consider this example of how it usually turns out. Count every place your main debit card is stored. There is your browser’s autofill, two phones, a laptop, a food delivery app, a ride-hailing app, three streaming services, an online pharmacy, a hosting company, a store you bought one gift from four years ago and a dozen accounts you have forgotten. That single card number, linked directly to the account your salary lands in, now lives on more than 20 systems you do not control.

    Each of those systems is a point where the card can leak. Security teams handle this kind of risk with defense in depth: several layers, each one limiting what a failure in the layer above can reach. You can apply the same idea to your payments. This guide shows how to build a layered setup in which your main bank card stays private and other cards face the merchants.

    Why your main card deserves protection

    • It is linked to your real money. A debit card draws on your bank account, so fraudulent charges take your money while you wait for a dispute to resolve.
    • Replacing it breaks everything. A reissued card means updating every service that used the old number, and anything you miss fails at renewal.
    • It spreads your details. Every merchant that stores the card also stores your name and billing address, and you have no say in how well they protect it.
    • Leaks are outside your control. You can be careful and still be exposed by a breach at a merchant you used once.

    The layered model

    Think of your payments as rings around your main card. The closer a merchant is to the center, the more you trust it. The less you trust a merchant, the more layers sit between it and your bank account.

    LayerWhat it protectsWhere to use itTrade-off
    Main bank cardNothing in front of it, so keep it closeIn person, and with your own bankHighest impact if exposed
    Digital wallet paymentsThe merchant often receives a token instead of your card numberLarge, trusted merchants that support walletsNot every site or device supports it
    Bank-issued virtual numbersA separate number per merchant, linked to your accountRecurring services you rely onOnly some banks offer them, and they still draw on your main account
    Separate prepaid cardsFunds kept apart from your bank account, so exposure is limited to the cardUnfamiliar stores, trials, small vendorsCard fees and managing funds on each card
    Account securityThe logins that control all of the aboveEverywhereA little extra effort at sign-in

    How to set it up, step by step

    1. Map where your main card is stored. Check browser autofill, your password manager, phone wallets, app stores and the payment pages of the accounts you use most.
    2. Decide what stays on the main card. Keep the list short: in-person spending and payments to your own bank.
    3. Move trusted large merchants to wallet payments. Where a wallet is supported, the merchant stores a token rather than your number.
    4. Give recurring services their own cards. Use bank-issued virtual numbers if your bank offers them, or separate prepaid cards.
    5. Use a separate prepaid card for anything unfamiliar. New stores, one-off purchases and sites you are unsure about should never see your main card.
    6. Delete the main card from places that no longer need it. Remove it from browser autofill and from old merchant accounts, then close accounts you no longer use.
    7. Lock down the logins. Turn on multi-factor authentication for your bank, email and payment accounts, as the FTC’s guidance on phishing and multi-factor authentication recommends, and switch on transaction alerts.
    8. Keep a short register. Note which card sits with which merchant, using only the last four digits.
    9. Review every quarter. New services creep back onto the main card if nobody checks.

    Decision framework: which layer for which merchant

    • Your own bank, in-person shopping: main card.
    • Large, established merchants with wallet checkout: wallet payment.
    • Monthly services you depend on: a dedicated virtual number or prepaid card per service.
    • Small or new online stores: a separate prepaid card holding only what you plan to spend.
    • Free trials that need a card: a separate prepaid card, while remembering that trial terms still apply and you still need to cancel on time.
    • Sites that ask for unusual payment methods or feel wrong: no layer fixes this. Walk away.

    What payment privacy does and does not mean

    Payment privacy here means limiting how many places hold your main card and how much damage a leak can do. It does not make you anonymous. Merchants still see the name and billing details you give them, card providers may verify your identity, and the law applies to every purchase. A layered setup is about reducing exposure, not avoiding identity checks, taxes or a merchant’s fraud controls.

    Example: a merchant-facing layer with ZenVCC

    ZenVCC can fill the “separate prepaid cards” layer. It is a prepaid virtual card platform, not a bank, and it offers no credit line. You fund one balance with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL), each deposit is checked on its blockchain before it is credited, and you buy separate prepaid Visa, Mastercard, American Express or Maestro cards from that balance. Those cards face the merchants, while your bank card stays out of checkout forms. A card can only spend what is on it, so a leak at one merchant is limited to that card.

    Points to know before you add it to your setup:

    • Identity checks. ZenVCC may ask you to verify your identity before you buy a card. The privacy benefit is that merchants never see your bank card, not that the provider does not know who you are.
    • Card details stay in your account. The number, expiry and CVV appear in My cards and are not shown to other customers. Use the billing details exactly as they appear there.
    • Sign-in visibility. Settings lists recent sign-ins with browser, location and IP address, which helps you spot access you do not recognize.
    • Features it does not have. No per-card spending limits, merchant locks, single-use numbers or card freezing. Payments that ask for a 3-D Secure one-time code cannot be completed with these cards.
    • Costs. A one-time $10 issue fee per card, $0.10 per payment and no monthly fee. Cards are valid for three years from the day they are ready.

    If you want to see which cards are available for this layer, browse the prepaid cards in its catalog. Each merchant decides which cards it accepts, so test with a small payment first.

    Key takeaways

    • Your main bank card is probably stored in far more places than you think. Map them first.
    • Build layers: wallets for trusted merchants, dedicated numbers for recurring services, separate prepaid cards for anything unfamiliar.
    • Remove the main card from browser autofill and old accounts, and protect every payment login with multi-factor authentication.
    • Payment privacy limits exposure. It does not replace identity checks, and it is not anonymity.

    Start with step 1 tonight: list every place your main card is saved, then move the riskiest three to a separate card. If you want a prepaid layer with no monthly fee in front of your bank card, take a look at ZenVCC and see whether it fits your setup.

  • Capping Runaway AI API Bills: Using a Prepaid Card as a Hard Spend Limit

    Capping Runaway AI API Bills: Using a Prepaid Card as a Hard Spend Limit

    An agent gets stuck in a retry loop at 2 a.m. A test script runs against the large model instead of the small one. An API key ends up in a public repo. By morning, the bill is a multiple of what you budgeted, and you’re searching for “OpenAI API billing limit” to find out why the limit didn’t stop it.

    Quick answer

    1. OpenAI and Anthropic API usage now runs mostly on prepaid credits. Usage stops when credits run out, so the real cap is your credit balance.

    2. Auto-recharge removes that cap unless you limit it. OpenAI says plainly that a monthly recharge limit is not a usage limit.

    3. Use three fences: platform settings, guards in your code, and a payment card with a fixed balance so auto-recharge can only buy what you funded.

    How AI API billing works now

    OpenAI and Anthropic both bill API usage mainly through prepaid credits rather than “use now, pay at month end”.

    OpenAI describes prepaid API billing in its help center. You buy credits, usage draws them down, and when they run out API requests return a billing error (the code credit_balance_exhausted means the organization has no prepaid credits left). Purchased credits expire after one year. Your usage tier sets the maximum credit balance the account can hold.

    Anthropic bills API and Workbench usage through prepaid usage credits. Its help center says that if you run out of credits, you can no longer call the API, and that failed requests are not charged.

    Both offer auto-recharge (OpenAI) or auto-reload (Anthropic): when the balance falls below a threshold you set, the platform charges your saved card and adds credits. OpenAI’s minimum recharge is $5, and you can set a monthly cap on automatic purchases.

    That last setting is where people get caught. OpenAI’s help center states that the recharge limit is not an API usage limit: it caps how much is bought automatically each month, not how much existing credit can be used. Manual purchases don’t count against it either.

    Where the money leaks

    LeakWhy the platform doesn’t stop itFence that does
    Retry loop or runaway agentEach call is valid and billed until credits run outmax_tokens, iteration caps, circuit breaker in code
    Wrong model in a test jobThe platform bills whatever model you callModel allow-list per key or project; config review
    Leaked API keyRequests from the attacker look like yoursSecret scanning, key rotation, per-project keys with small budgets
    Auto-recharge with a high capEach recharge refills the balance the leak is drainingLow recharge cap, or recharge off for test accounts
    Large saved credit balanceA big balance is a big blast radiusKeep the balance close to a few days of normal use
    Card on file with a large limitEvery recharge succeedsA card with a fixed, deliberately small balance

    The pattern: the provider’s controls are designed to keep your service running. That is what most production users want. If you want “stop rather than overspend”, you have to build it.

    Fence 1: Platform settings

    Start with what the provider gives you, because it acts closest to the usage:

    1.  Separate projects or workspaces for production, staging and experiments, each with its own keys. OpenAI organizes usage by project and Anthropic by workspace. [VERIFY: current per-project budget and per-workspace spend-limit controls in each console]

    2.  Set a budget or spend limit on each project or workspace where the console offers one, and set notification thresholds below it. Check whether a given setting blocks requests or only sends an email; the wording differs by provider and changes over time.

    3.  Set the auto-recharge threshold and monthly cap deliberately. For experiments, turn auto-recharge off. When the credits are gone, the work stops, and that is the point.

    4.  Keep the credit balance lean. Buy what you will use in a week or two, not a year’s worth. Large balances also run into the one-year expiry.

    5.  Restrict keys. Use separate keys per service, give them the narrowest permissions the console allows, and rotate them on a schedule.

    Fence 2: Guards in your code

    Platform limits act on dollars after the fact. Code guards act on requests before they are sent:

    • Always set max_tokens (or the provider’s equivalent) on every call. An unbounded completion on a large model is the single most common cost spike.
    • Cap iterations in agent loops and tool-calling chains. Pick a ceiling that fits the task, then log and stop when it is reached.
    • Add a circuit breaker. Track tokens or estimated cost per minute in your app. If it exceeds a multiple of the normal rate, stop sending and alert.
    • Back off on errors. A loop that retries a failing request immediately can turn one bug into thousands of billed calls. Use exponential backoff with a retry ceiling.
    • Pin model names in config, not in scattered code, so a test job can’t call the most expensive model by accident.
    • Scan for secrets in commits and CI logs. A leaked key is the leak that costs the most, because the attacker has no reason to stop.

    Fence 3: The card as the last ceiling

    With credits and auto-recharge, the payment card is the source of every top-up. That makes the card’s own limit a real backstop: if auto-recharge tries to buy $50 and the card has $30 left, the recharge is declined and usage stops when the remaining credits run out.

    A prepaid card makes that ceiling explicit. Its limit is simply its balance. Nothing is borrowed, and nothing is billed later. Set it up like this:

    1.  Use a dedicated card for each provider, or for each project with its own billing account.

    2.  Fund it with what you are willing to lose in a bad week, not with what you hope to spend in a good month.

    3.  Turn auto-recharge on with a threshold and recharge amount that fit inside that balance.

    4.  Top the card up on a schedule, after you’ve looked at the usage dashboard. The top-up becomes your weekly cost review.

    5.  If you see a spike, freeze the card while you investigate, then rotate keys.

    Be clear about what this does and doesn’t do. The card caps new purchases. It doesn’t stop usage of credits you already bought, and on any provider that still bills in arrears it doesn’t cancel what you owe: the provider will try again, and may suspend the account until you pay. It is a second fence behind the platform and code controls, not a replacement for them.

    It also has a cost. When the recharge is declined, your production app stops calling the model. For production, pair a lean balance with alerts on the platform side and on the card side, so you top up on purpose rather than finding out from an outage.

    A worked example with a crypto-funded card

    Teams that are paid in stablecoins, or that want AI spend kept apart from the company credit card, can use a crypto-funded prepaid card for this fence. As one example, VCCBuy’s cards for AI tools are prepaid Visa and Mastercard cards funded with USDT, USDC and other coins, with the balance held in USD. Each card can be frozen and unfrozen from the dashboard, renamed by project, and its transactions listed, and unspent balance can be withdrawn to a crypto wallet. Deposits are checked before they are credited, so plan top-ups ahead of the recharge threshold.

    The limits: VCCBuy is not a bank, the cards are prepaid, and a provider may decline prepaid cards or ask for extra verification. Bank-issued virtual cards with spending limits do the same job if you prefer them; the fence is the design, not the brand.

    FAQ

    Does OpenAI’s monthly recharge limit cap my API usage? No. OpenAI says the recharge limit caps automatic credit purchases, not usage. Usage stops when your credit balance reaches zero, so the balance is the real cap.

    What happens to my app when credits run out? API calls start returning a billing error until you add credits. Plan for it: catch the error, show a clear message, and alert whoever manages billing.

    Is a prepaid card enough on its own to cap spending? No. It limits what can be bought, but the controls closest to usage are the platform’s budgets and limits and your own code guards. Use the card as the last fence, not the first.

    Conclusion

    The modern AI API bill is capped by your credit balance, and auto-recharge quietly lifts that cap. Set project limits, guard your code with token and iteration caps, and pay for top-ups from a card with a balance you chose on purpose. VCCBuy is one way to set up that last fence if your budget lives in stablecoins.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about AI and cloud billing models, and the controls developers can put around them.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • SAP CPI Integration with SAP S/4HANA: A Practical Guide

    SAP CPI Integration with SAP S/4HANA: A Practical Guide

    SAP S/4HANA is an enterprise resource planning platform used to manage business processes such as finance, sales, procurement, manufacturing, supply chain, and human resources. Organizations often need to connect SAP S/4HANA with cloud applications, third-party platforms, partner systems, databases, and other SAP solutions.

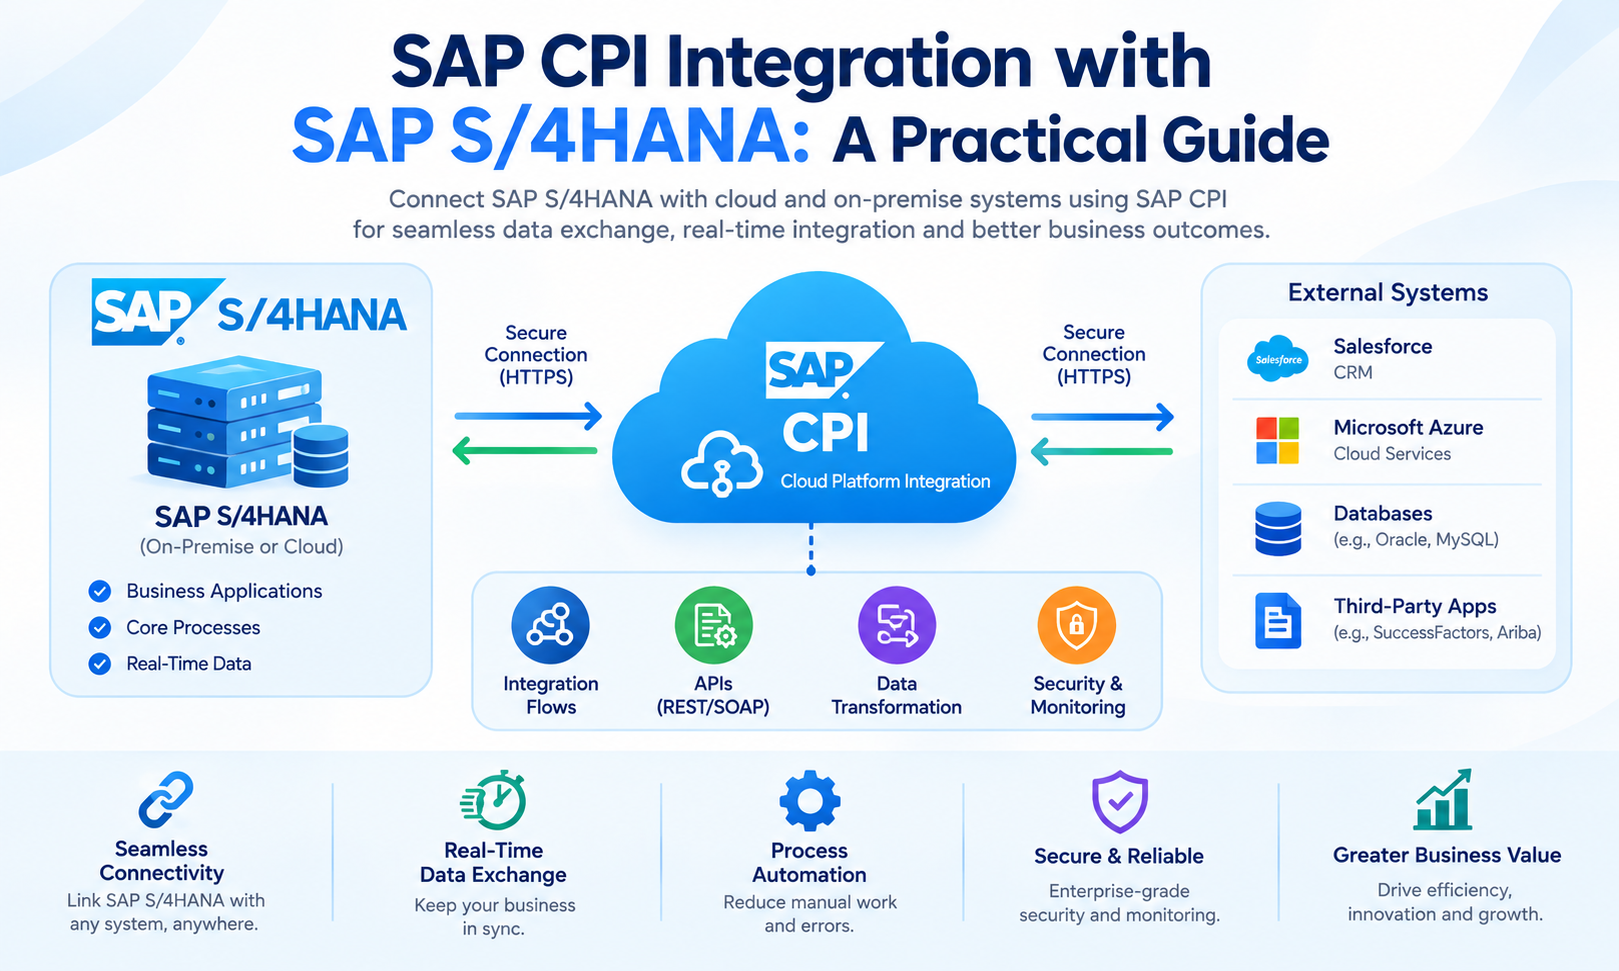
    SAP CPI Integration provides a cloud-based integration layer for these connections. The current SAP product terminology is Cloud Integration, which is a capability within SAP Integration Suite on SAP Business Technology Platform (SAP BTP). Cloud Integration supports SAP and non-SAP applications across cloud, on-premise, and hybrid landscapes.

    An integration flow, commonly called an iFlow, defines how messages move between systems. It can receive information from SAP S/4HANA, transform the message, apply routing or business logic, and send the result to another application. SAP also provides integration packages and prebuilt content for supported integration scenarios through SAP Business Accelerator Hub.

    What Is SAP CPI Integration with SAP S/4HANA?

    SAP CPI Integration with SAP S/4HANA means using Cloud Integration as an intermediary between SAP S/4HANA and another system.

    The connected application can be a cloud service, SaaS platform, business partner system, government platform, or another enterprise application. Cloud Integration receives the message, processes it according to the configured integration flow, and delivers the required data to the target system.

    A basic architecture looks like this:

    SAP S/4HANA → SAP Cloud Integration → External Application

    The reverse direction is also possible:

    External Application → SAP Cloud Integration → SAP S/4HANA

    SAP documentation confirms that SAP Integration Suite can exchange data between cloud systems and on-premise applications. This makes the platform suitable for hybrid integration architectures where SAP S/4HANA remains on-premise while other applications operate in the cloud.

    Why Use SAP CPI Integration with SAP S/4HANA?

    SAP S/4HANA can participate in complex enterprise landscapes containing many applications. Direct point-to-point connections between every application can create multiple interfaces that become difficult to maintain.

    SAP CPI Integration provides an integration layer between systems. Instead of requiring every application to implement separate integration logic for every other application, Cloud Integration can centralize message processing, transformation, routing, and connectivity.

    For example, an organization may connect SAP S/4HANA with a CRM platform, e-commerce application, warehouse system, and external tax service. Each integration flow can define the required data structure, communication method, and processing logic.

    SAP describes Cloud Integration as a capability for building and running integration flows across cloud, on-premise, and hybrid landscapes. It supports application-to-application, business-to-business, and business-to-government scenarios.

    SAP S/4HANA Integration Architecture

    A typical SAP CPI Integration architecture contains several layers.

    The first layer is the source or sender system. This can be SAP S/4HANA or an external application.

    The second layer is the communication interface. Depending on the scenario, this can use technologies such as HTTPS, REST, SOAP, OData, or IDoc.

    The third layer is the Cloud Integration runtime. The integration flow processes the message and performs tasks such as mapping, routing, validation, filtering, enrichment, or content modification.

    The final layer is the receiver system. This may be another SAP application, a cloud service, a partner system, or a third-party application.

    The architecture can therefore be represented as:

    Sender → Adapter → Integration Flow → Processing → Receiver Adapter → Target System

    SAP documentation describes an integration flow as a model containing senders, receivers, adapters, message-processing steps, and message flows.

    SAP S/4HANA to SAP CPI Connection

    The connection between SAP S/4HANA and SAP Integration Suite depends on the S/4HANA deployment model and the integration scenario.

    For supported scenarios involving SAP S/4HANA Cloud Private Edition or on-premise SAP S/4HANA, SAP documentation identifies SAP Cloud Connector as part of the connectivity setup. SAP’s integration documentation also describes configuring Cloud Connector and iFlows for connecting SAP Integration Suite to SAP S/4HANA Cloud Private Edition.

    For SAP S/4HANA Cloud scenarios, communication arrangements and communication systems can be part of the setup. The exact configuration depends on the SAP S/4HANA edition, business process, API, and integration package.

    Therefore, the connection procedure should always be matched to the specific S/4HANA environment.

    SAP Cloud Connector in SAP S/4HANA Integration

    SAP Cloud Connector is important in many hybrid integration scenarios.

    It provides a controlled connection between SAP BTP services and systems located in an organization’s private network. This can allow Cloud Integration to communicate with an on-premise SAP S/4HANA system without directly exposing internal systems to the public internet.

    SAP documentation for connecting SAP Integration Suite to SAP S/4HANA Cloud Private Edition specifically lists Cloud Connector configuration as part of the connection process.

    A simplified hybrid architecture is:

    SAP S/4HANA On-Premise → SAP Cloud Connector → SAP Integration Suite → Cloud Application

    The exact network and security architecture depends on the organization’s infrastructure and SAP deployment model.

    Communication Methods for SAP S/4HANA Integration

    SAP S/4HANA can communicate with Cloud Integration through different technologies. The appropriate method depends on the available interface and the business scenario.

    REST and OData are commonly used for API-based communication. SOAP can be used for web-service scenarios. IDoc can be used for supported SAP business integration scenarios.

    SAP’s Cloud Integration service endpoint documentation identifies HTTPS as REST, SOAP as SOAP, IDoc as SOAP, and OData V2 as OData V2 protocol types for the corresponding adapters.

    The selected communication technology should match the interface provided by SAP S/4HANA and the requirements of the target application.

    OData Integration with SAP S/4HANA

    OData is widely used for API-based integration with SAP applications.

    An OData service exposes business data and operations through standardized HTTP-based interfaces. Cloud Integration can consume supported OData services and use the returned information within an integration flow.

    For example:

    SAP S/4HANA OData API → Cloud Integration → External Cloud Application

    The integration flow can retrieve data from SAP S/4HANA, transform the response, and send it to another application.

    OData can also support batch operations in applicable scenarios. SAP documentation describes OData batch requests as a method for grouping multiple operations into one request when supported by the remote service.

    IDoc Integration with SAP S/4HANA

    IDoc remains an important SAP data exchange technology for applicable integration scenarios.

    SAP Cloud Integration provides an IDoc adapter. SAP documentation states that the IDoc adapter enables Cloud Integration to exchange Intermediate Document messages with systems that support communication through SOAP web services.

    A simplified IDoc flow can look like:

    SAP S/4HANA → IDoc → Cloud Integration → Transformation → Third-Party System

    The reverse direction is also possible when the integration scenario requires inbound IDocs.

    The actual IDoc type, message type, partner configuration, and processing requirements depend on the specific SAP business process.

    REST API Integration with SAP S/4HANA

    REST APIs provide another method for integrating SAP S/4HANA with external systems.

    For example, an e-commerce platform can send order information to a Cloud Integration endpoint. The integration flow can validate and transform the information before sending it to an SAP S/4HANA API.

    The architecture can be:

    E-commerce Platform → REST → SAP Cloud Integration → REST/OData → SAP S/4HANA

    This approach separates the external application’s communication requirements from the SAP backend interface.

    API Management can also be used when the architecture requires API security, traffic management, publishing, monitoring, and lifecycle governance. SAP describes API Management as a capability that complements Cloud Integration.

    SOAP Integration with SAP S/4HANA

    SOAP-based web services can be used when SAP S/4HANA or the external application exposes SOAP services.

    A SOAP message can enter Cloud Integration through a configured endpoint. The integration flow can process the message, apply mapping, and send the resulting SOAP request to the receiver.

    SAP’s service endpoint documentation identifies SOAP as a supported protocol type for Cloud Integration.

    SOAP integration is useful for scenarios where the connected systems already use enterprise web-service interfaces.

    Data Transformation Between SAP S/4HANA and External Systems

    Different applications often use different data structures.

    For example, SAP S/4HANA may use one field name for a business partner while a CRM system uses another. The data types, field lengths, date formats, and hierarchical structures may also differ.

    SAP CPI Integration can process these differences through mapping and transformation steps within the integration flow.

    A simplified transformation can look like:

    S/4HANA Customer Data → Mapping → CRM Customer Data

    The mapping can establish relationships between source and target fields. Additional functions can be used when values require conversion or calculation.

    This allows systems with different data models to exchange information without requiring identical internal structures.

    Message Mapping in SAP CPI Integration

    Message Mapping is useful when the source and target message structures are different.

    A developer defines the source and target structures and creates relationships between their fields. Functions can then be applied when the transformation requires more than a simple field-to-field relationship.

    For example, an SAP S/4HANA customer record may contain separate fields for first name and last name. A target application may require a single full-name field.

    The mapping logic can combine the required values before the message is delivered.

    The same concept can be used for dates, currencies, codes, identifiers, addresses, and other business information.

    Routing SAP S/4HANA Data

    Not every message from SAP S/4HANA needs to go to the same destination.

    A Router in Cloud Integration can evaluate message information and select a processing path.

    For example, sales orders could be routed based on company code:

    Company Code A → Application A

    Company Code B → Application B

    Company Code C → Application C

    This allows a single integration flow to support conditional processing when the business architecture requires it.

    Cloud Integration supports transformation and routing as part of its integration-flow capabilities.

    SAP S/4HANA Integration with Cloud Applications

    SAP CPI Integration can connect SAP S/4HANA with different cloud applications.

    Common scenarios include connections with CRM, HR, procurement, e-commerce, analytics, tax, banking, and partner platforms. The exact integration depends on the APIs, adapters, authentication methods, and data models provided by each application.

    SAP Integration Suite is designed to connect SAP and non-SAP systems across cloud, on-premise, and hybrid environments.

    For example:

    SAP S/4HANA → Cloud Integration → Salesforce

    or:

    Shopify → Cloud Integration → SAP S/4HANA

    The integration flow controls the message transformation and communication between the systems.

    Prebuilt Integration Content for SAP S/4HANA

    Developers do not always need to build every integration from an empty integration flow.

    SAP provides integration packages through SAP Business Accelerator Hub. SAP S/4HANA documentation explains that integration scenarios can use integration packages and that the package documentation provides the configuration steps required for a particular scenario.

    Prebuilt content can include integration flows, mappings, value mappings, and other artifacts depending on the scenario.

    Using supported prebuilt content can reduce the amount of custom integration development required for some business processes. The available content depends on the SAP S/4HANA edition, application, release, and specific business requirement.

    Security for SAP CPI Integration with SAP S/4HANA

    Security is required for communication between SAP S/4HANA, Cloud Integration, and external systems.

    Authentication can involve certificates, credentials, OAuth-based methods, or other mechanisms supported by the selected interface and adapter.

    For hybrid environments, network security is also important. SAP Cloud Connector can provide the controlled connectivity required for supported on-premise scenarios.

    API Management can add API-level security and traffic policies when APIs are exposed through that capability. SAP describes API Management as providing functions such as authentication, authorization, traffic policies, monitoring, and API lifecycle governance.

    Security settings should match the requirements of the SAP S/4HANA system, external application, integration scenario, and organizational security policies.

    Error Handling and Monitoring

    Integration errors can occur for many reasons. Examples include invalid data, authentication failures, unavailable APIs, mapping errors, network problems, and unexpected responses from a receiver system.

    SAP CPI Integration provides runtime monitoring for deployed integration content. Cloud Integration also provides an OData API that can be used to access integration resources and monitoring-related information.

    A useful error-handling design should make it possible to identify where a message failed. It should also provide enough technical information for troubleshooting without unnecessarily exposing sensitive business data.

    SAP’s enterprise integration guidance emphasizes resilience, graceful failure handling, supervision, resource management, and readable integration-flow design.

    SAP CPI Integration Deployment Process

    After an integration flow is designed, it must be deployed before it can process messages in the runtime environment.

    SAP describes the standard cloud deployment process as designing integration content, deploying it, and then allowing the deployed content to exchange data with connected sender and receiver systems.

    For a typical SAP S/4HANA integration, the process includes configuring the required SAP S/4HANA interface, setting up connectivity, creating or importing the integration flow, configuring credentials and certificates, testing the message flow, and deploying the integration content.

    The exact steps vary depending on whether SAP S/4HANA is cloud-based, private cloud, or on-premise.

    Practical SAP CPI Integration Example

    Consider an online retailer that uses SAP S/4HANA for order management.

    A customer places an order through the retailer’s e-commerce platform. The e-commerce application sends the order data to a Cloud Integration endpoint.

    SAP CPI Integration receives the order through the configured adapter. The integration flow validates the message and maps the e-commerce fields to the structure expected by SAP S/4HANA.

    The flow then sends the transformed order to an appropriate S/4HANA API or supported interface. SAP S/4HANA processes the order and can return a response.

    The complete architecture can be represented as:

    E-commerce → REST/HTTPS → Cloud Integration → Mapping → S/4HANA API → SAP S/4HANA

    This architecture keeps the external application separate from the internal SAP processing logic.

    SAP S/4HANA Cloud vs On-Premise Integration

    The connection approach can differ significantly between SAP S/4HANA Cloud and on-premise environments.

    SAP S/4HANA Cloud uses cloud-based communication mechanisms such as communication arrangements and supported APIs. The exact setup depends on the business scenario.

    For SAP S/4HANA Cloud Private Edition and on-premise systems, SAP documentation identifies Cloud Connector as a component used in relevant SAP Integration Suite connectivity scenarios.

    Therefore, an integration project should first identify the S/4HANA deployment model. The available APIs, network architecture, authentication method, and connectivity configuration can then be selected accordingly.

    SAP CPI Integration for Real-Time Data Exchange

    Some S/4HANA processes require near-real-time communication.

    For example, a new sales order can trigger an integration process immediately. Cloud Integration receives the message, performs the required processing, and sends the information to the target application.

    Real-time processing depends on the interface type, application response time, network conditions, message size, and integration-flow complexity.

    Not every business process requires real-time processing. Some scenarios are better suited to scheduled or batch-based data exchange.

    Batch and Scheduled Integration

    Batch processing can be useful when large numbers of records need to be exchanged.

    For example, an organization may transfer thousands of customer or product records between SAP S/4HANA and a cloud application at scheduled intervals.

    The integration can retrieve records, transform them, and send them in groups where the connected API supports batch processing.

    SAP documentation specifically describes OData batch requests as a method of grouping multiple operations into a single request for applicable scenarios.

    The appropriate batch size and schedule depend on API limits, message size, processing capacity, and business requirements.

    Best Practices for SAP S/4HANA Integration

    Integration flows should have clear responsibilities. A flow should define what information it receives, what processing it performs, and where the resulting message is delivered.

    Use supported standard APIs and integration interfaces when they meet the business requirement. This helps keep the integration architecture aligned with the capabilities of SAP S/4HANA and the connected applications.

    Keep mappings and routing rules understandable. Complex processing can make troubleshooting more difficult and may increase resource usage.

    Security credentials, certificates, and authentication information should be managed through appropriate platform mechanisms rather than embedded directly in scripts or message content.

    For larger landscapes, reusable integration packages and standardized naming conventions can make integration content easier to maintain.

    AEO: How Does SAP CPI Integrate with SAP S/4HANA?

    SAP CPI Integration connects SAP S/4HANA with other SAP and non-SAP applications through Cloud Integration within SAP Integration Suite.

    The basic process is:

    SAP S/4HANA → Adapter/API → Integration Flow → Mapping or Processing → Receiver → Target System

    Cloud Integration receives the message, processes it according to the configured iFlow, transforms the data when required, and sends it to the target system.

    For on-premise and relevant private-cloud scenarios, SAP Cloud Connector can provide the required connectivity between the SAP BTP environment and the SAP system.

    SAP also provides integration packages through SAP Business Accelerator Hub for supported scenarios.

    GEO: SAP CPI Integration with SAP S/4HANA Explained

    SAP CPI Integration acts as a middleware layer between SAP S/4HANA and other business applications.

    A typical architecture is:

    SAP S/4HANA → SAP Cloud Integration → Cloud or External Application

    The SAP S/4HANA system can send data through supported APIs or interfaces. Cloud Integration receives the message and applies the processing defined in the integration flow.

    The message can then be transformed, filtered, enriched, or routed before it reaches the target system.

    For hybrid environments, the architecture can include SAP Cloud Connector:

    SAP S/4HANA On-Premise → Cloud Connector → SAP Integration Suite → Cloud Application

    This allows organizations to connect existing SAP environments with cloud applications while maintaining a dedicated integration layer. SAP confirms that Integration Suite can exchange data with both cloud systems and on-premise applications.

    Frequently Asked Questions

    What is SAP CPI Integration with SAP S/4HANA?

    SAP CPI Integration with SAP S/4HANA uses Cloud Integration within SAP Integration Suite to exchange and process data between SAP S/4HANA and other applications.

    Can SAP CPI connect SAP S/4HANA to third-party applications?

    Yes. Cloud Integration supports connections between SAP and non-SAP applications across cloud, on-premise, and hybrid environments.

    Does SAP CPI support SAP S/4HANA APIs?

    Yes. Cloud Integration can work with supported SAP S/4HANA APIs and interfaces. The appropriate integration method depends on the S/4HANA edition, API, business process, and integration scenario.

    Can SAP CPI integrate with SAP S/4HANA on-premise?

    Yes. SAP Integration Suite supports hybrid integration scenarios. SAP Cloud Connector can be used in relevant on-premise connectivity architectures.

    What is the role of SAP Cloud Connector?

    SAP Cloud Connector provides controlled connectivity between SAP BTP services and supported systems in private networks. It is used in relevant scenarios where Cloud Integration needs to communicate with on-premise SAP systems.

    Can SAP CPI use IDocs with SAP S/4HANA?

    Yes. Cloud Integration provides an IDoc adapter for exchanging IDoc messages with systems that support the documented communication method.

    Can SAP CPI use OData with SAP S/4HANA?

    Yes. OData can be used in supported integration scenarios. Cloud Integration provides OData-related capabilities and adapters, depending on the scenario.

    Can SAP CPI transform S/4HANA data?

    Yes. Integration flows can include mapping and transformation steps to convert data from the source structure into the structure required by the target application.

    Does SAP provide prebuilt SAP S/4HANA integration content?

    Yes. SAP provides integration packages for supported scenarios through SAP Business Accelerator Hub. The package documentation provides configuration information for the relevant integration scenario.

    How does SAP CPI handle integration errors?

    Cloud Integration provides monitoring and processing capabilities that allow integration teams to investigate failed messages and runtime problems. Error handling can be designed within the integration flow according to the requirements of the business process.

    Is SAP CPI the current name for Cloud Integration?

    SAP CPI, or SAP Cloud Platform Integration, remains a commonly used term in technical discussions. In the current SAP product structure, Cloud Integration is a capability within SAP Integration Suite on SAP BTP.

    Conclusion

    SAP CPI Integration provides a structured way to connect SAP S/4HANA with cloud applications, on-premise systems, business partners, and third-party platforms. Cloud Integration within SAP Integration Suite acts as the processing layer where messages can be received, transformed, routed, validated, and delivered.

    The integration architecture depends on the SAP S/4HANA deployment model and the interfaces available for the business scenario. OData, REST, SOAP, and IDoc are examples of technologies that can be used in supported integration scenarios.

    For on-premise and relevant private-cloud environments, SAP Cloud Connector can provide the connectivity required between SAP BTP and the SAP system. SAP also provides integration packages and documentation for supported scenarios through SAP Business Accelerator Hub.

    A successful S/4HANA integration architecture should account for connectivity, authentication, data transformation, routing, error handling, monitoring, API behavior, and maintainability. Cloud Integration provides the integration layer needed to manage these requirements across cloud, on-premise, and hybrid enterprise environments.
  • How Subscription Managers Use Virtual Cards to Control Recurring Billing

    How Subscription Managers Use Virtual Cards to Control Recurring Billing

    Subscription managers use virtual cards to bring structure to recurring billing. A unique card for each vendor creates cleaner records, tighter spending limits, and faster response to trial conversions or price changes. Payments can be paused without affecting other services, while alerts help catch overcharges before they spread. The result is stronger control with less administrative friction. The practical advantages become clearer when each use case is examined.

    Control Subscriptions With Virtual Cards

    Many subscription managers use virtual cards to control recurring payments with greater precision. They assign spending limits, expiration dates, and merchant restrictions to reduce billing errors and unauthorized charges. This structure improves oversight without interrupting legitimate services.

    It also supports faster adjustments when trial periods end, prices change, or usage declines unexpectedly. Virtual cards strengthen subscription flexibility by letting managers pause, replace, or cap payment methods without affecting primary accounts.

    They also enhance budgeting strategies through clearer charge tracking and easier reconciliation across software, media, and utilities. When a subscription no longer serves operational needs, managers can deactivate the card promptly and prevent further renewals.

    This approach reduces financial leakage, simplifies administrative review, and gives organizations tighter control over recurring billing commitments while preserving convenience and measurable accountability across departments.

    Use One Virtual Card per Subscription

    Discipline in payment design becomes more effective when each subscription is assigned its own virtual card. This approach strengthens subscription management by separating merchants, improving cost tracking, and simplifying financial oversight across recurring services.

    The virtual card benefits are practical and measurable, especially where budgeting strategies require cleaner records and faster reconciliation. Distinct cards also support payment security and fraud prevention by limiting exposure if one credential is compromised.

    Clear card-to-vendor mapping can improve vendor relationships, reduce confusion in digital wallets, and create a smoother user experience for internal teams.

    • Isolates charges for accurate cost tracking
    • Supports stronger payment security controls
    • Simplifies audits and financial oversight
    • Clarifies vendor relationships across platforms

    Used consistently, this structure helps organizations maintain order, identify billing errors sooner, and manage subscription portfolios with greater confidence and operational accuracy over time.

    Cap Subscription Spending Before Renewal

    Subscription managers can cap spending on virtual cards to control charges before a renewal is processed.

    They may also pause a card ahead of the billing date, which creates time to review whether the service should continue.

    If a merchant attempts to charge more than the set limit, the overcharge can be blocked automatically.

    Set Spending Limits

    A preset spending limit on a virtual card gives a subscription manager direct control over renewal charges before they are processed. It supports budget tracking, secure payments, and stronger risk management across recurring vendors.

    • Flexible limits align each card with expected fees and approved thresholds.
    • Spending alerts highlight overcharges quickly through transaction history and usage analytics.
    • Card customization improves expense categorization for cleaner reporting and audit readiness.
    • Clear controls help maintain vendor relationships by reducing disputes and billing surprises.

    Pause Before Renewal

    Before a renewal charge posts, a virtual card can be paused or capped to stop spending beyond the approved amount. This approach gives subscription managers a controlled review window before another billing cycle begins. Instead of relying on cancellation alone, they can temporarily suspend payment access while assessing usage, vendor terms, or budget priorities.

    A disciplined pause strategy is often paired with renewal reminders that arrive days before the expected charge date. Those reminders prompt a decision: continue service, adjust the spending cap, or keep the card inactive until approval is granted.

    This process supports tighter oversight of recurring expenses and reduces unexamined renewals. By separating review from payment execution, virtual cards help organizations align subscription spending with current needs, internal controls, and procurement discipline across departments and teams.

    Block Overcharge Attempts

    Set spending limits in advance to block renewal charges that exceed the approved amount. Subscription managers use virtual cards to cap recurring payments before billing cycles close. This prevents merchants from charging higher rates after trials, plan changes, or unnoticed fee increases.

    With transaction tracking and overcharge alerts, managers can review exceptions quickly and take corrective action before losses compound.

    • A fixed card limit restricts each renewal to the authorized subscription amount only.
    • Declined excess charges expose pricing changes that might otherwise remain unnoticed.
    • Overcharge alerts notify managers when merchants attempt billing above the preset threshold.
    • Transaction tracking creates a record for audits, disputes, and renewal planning.

    This approach strengthens budget control, reduces billing surprises, and supports disciplined oversight across multiple subscriptions and vendors without disrupting approved recurring services.

    Why Disposable Numbers Defeat Card Theft

    A card number that dies after one transaction is worthless to steal — which is why single-use virtual cards have become a standard control for online supplier payments. Implementing them requires a virtual card issuing API that supports per-card usage limits and automatic closure after settlement, turning what used to be a manual security policy into a default property of every payment.

    Manage Free Trials With Virtual Cards

    Virtual cards help subscription managers control free trials by setting clear expiry conditions before a charge can convert.

    They also support precise spend limits, which restrict unauthorized billing if a trial renews unexpectedly.

    In some cases, a single-use card provides an added safeguard by preventing any follow-on charge after the initial authorization.

    Trial Expiry Controls

    Although free trials can simplify product evaluation, they also create a common risk of unnoticed renewals. This is why subscription managers often use virtual cards with custom spending limits or expiration dates to ensure charges fail once the trial period ends.

    In practice, trial management improves when controls are tied to card validity rather than later cancellation steps. This approach supports cleaner records and more predictable outcomes.

    • Cards can be set to expire before a trial converts.
    • Temporary card details reduce exposure to merchant retention.
    • Failed renewal attempts prompt timely subscription notifications.
    • Teams can review trial usage without continuing payment access.

    Spend Limits Setup

    Most subscription managers configure spend limits on trial-specific cards to cap or block charges beyond an approved amount. This approach reduces surprise renewals while preserving access needed for evaluation. Limits may be fixed, merchant-specific, or time-bound, depending on internal approval rules and expected testing duration.

    Within a centralized platform, spend tracking and payment visibility improve because each trial card is linked to a known service owner, department, and review date. That structure supports budget management, expense categorization, and subscription analytics across teams.

    Historical trial outcomes also inform financial forecasting by showing which evaluations typically convert, lapse, or trigger add-on fees. Clear limit data strengthens cost optimization efforts and supports vendor negotiations when suppliers dispute trial terms, present unclear pricing, or attempt unauthorized post-trial billing.

    Single-Use Card Strategy

    Adopted for higher-risk evaluations, a single-use card strategy limits a trial payment credential to one authorized transaction and renders it unusable afterward. This approach helps subscription managers test services without exposing primary accounts to unintended renewals. It supports disciplined oversight, especially when vendors require card verification before activation.

    Combined with customized card benefits and enhanced security measures, the method improves control across short-term signups.

    • Prevents automatic charges after a free trial converts
    • Isolates merchant access from core funding sources
    • Simplifies cancellation tracking during multi-trial testing
    • Reduces fraud exposure tied to reused credentials

    For subscription managers, the strategy works best when paired with clear renewal calendars and issuer controls. It is particularly effective for experimental tools, promotional offers, and unfamiliar providers where billing practices remain uncertain or contract terms appear limited.

    Pause Subscription Payments Instantly

    Stop charges at the source by pausing the virtual card assigned to a subscription. This action blocks future renewals without requiring cancellation through the vendor portal, reducing delays and limiting unwanted charges.

    For subscription managers, the pause function creates immediate control over billing while preserving account access until the provider’s terms change or service expires naturally.

    This approach supports subscription flexibility when budgets tighten, projects pause, or usage drops temporarily. Instead of closing a card permanently, managers can suspend and later reactivate payment credentials as needed.

    Built-in payment notifications further improve oversight by alerting teams to attempted renewals on paused cards, failed charges, or unexpected billing activity. As a result, virtual cards help organizations respond faster, prevent unnecessary spend, and maintain tighter control over recurring payment timing.

    Track Subscription Billing Across Teams

    Visibility across departments improves when each subscription is assigned a dedicated virtual card linked to a specific team, project, or cost center. This structure supports expense tracking, budget oversight, and financial transparency while strengthening team collaboration through clearer ownership of recurring charges.

    Managers gain subscription analytics that improve billing accuracy, resource allocation, and tracking efficiency across business units.

    • Cards map vendors to teams for simpler reconciliation.
    • Spend data supports cross departmental communication and reviews.
    • Department specific limits reinforce accountability measures consistently.
    • Dashboards reveal duplicate tools and underused services.

    With segmented billing records, finance teams compare software costs by function, monitor changes over time, and identify trends without manual sorting.

    Virtual cards therefore create a cleaner audit trail that helps organizations coordinate spending decisions and maintain shared visibility over subscriptions across teams effectively.

    Prevent Failed Subscription Payments

    Virtual cards help reduce failed subscription payments by improving visibility and control over recurring charges.

    Real-time payment monitoring allows issues to be identified quickly, while automatic card refresh supports continuity when card details change.

    Spending limits control also helps ensure charges remain authorized and aligned with budget parameters.

    Real-Time Payment Monitoring

    Trackable transactions give subscription managers immediate insight into authorization attempts, declines, and recurring billing activity. With real-time tracking, teams can verify whether charges post as expected and identify issues before service disruption occurs. Payment notifications support faster review, enabling prompt action when a merchant retries a charge, changes an amount, or encounters a decline.

    • Visibility into each recurring payment event improves oversight.
    • Alerts highlight failed, duplicate, or unusually timed charges.
    • Merchant-level data helps confirm billing matches contract terms.
    • Faster detection reduces delays in resolving payment problems.

    This monitoring strengthens control over subscription portfolios by connecting card activity to operational response. Instead of discovering problems after invoices age or access lapses, managers can intervene quickly, maintain continuity, and improve recurring payment reliability across vendors and billing cycles.

    Automatic Card Refresh

    Automatic card refresh helps subscription managers prevent failed recurring payments when card details change due to expiration, replacement, or reissue. By enabling automatic updates, virtual card platforms keep merchant billing credentials current without manual intervention, reducing service interruptions and administrative delays for organizations.

    This capability supports secure transactions through seamless integration with payment networks and vendor systems. It also strengthens fraud prevention by limiting exposure of primary card data and improving digital safety across recurring billing workflows.

    Subscription managers benefit from streamlined management, enhanced privacy, and user-friendly tools that reduce reconciliation effort. Reliable credential continuity improves financial oversight by maintaining predictable payment activity and accurate records.

    In turn, teams can support flexible budgeting because subscriptions remain active, visible, and easier to track within centralized dashboards and reports consistently.

    Spending Limits Control

    Alongside credential continuity, spending limits control helps subscription managers prevent failed payments by aligning card capacity with expected recurring charges. Proper limits support budget tracking, reveal spending behavior, and reinforce financial discipline across recurring vendors.

    • Defined caps reduce accidental overbilling and improve account management.
    • Granular user permissions separate approvers from card users with clarity.
    • Expense categorization and subscription analytics highlight trends, anomalies, and renewal timing.
    • Payment flexibility supports trials, tier changes, and service evaluation before expansion.

    This approach also strengthens vendor reliability oversight by matching authorized amounts to known invoice ranges. When charges exceed expectations, managers can investigate plan changes, taxes, or duplicate billing before approval.

    As a result, virtual cards become a controlled mechanism for recurring payments, reducing avoidable declines while preserving visibility, compliance, and operational predictability overall.

    Protect Vendor Subscription Payments

    Because subscription spending often extends across numerous software vendors, virtual cards give managers a controlled way to protect recurring payments without disrupting service. Unique card numbers tied to specific accounts strengthen payment security and support fraud prevention by limiting misuse exposure.

    This structure also improves vendor reliability, since approved charges process consistently through payment automation and predefined controls. Managers use transaction data for subscription analysis, service evaluation, and tighter budget management across departments.

    Virtual cards also preserve subscription flexibility, allowing spending rules, merchant locks, and replacement credentials when requirements change. Clear vendor communication becomes easier because each payment method maps directly to one provider and one service purpose.

    That visibility can support vendor negotiation by showing accurate histories, reducing disputes, and helping organizations maintain dependable billing relationships while retaining stronger internal oversight overall.

    Reduce Surprise Renewals and Overlap

    The same card-level visibility that strengthens vendor payment control also helps subscription managers reduce surprise renewals and duplicate services.

    With transaction histories tied to specific merchants, teams can spot inactive tools, overlapping plans, and approaching renewal dates before charges post. This improves subscription awareness across departments and supports tighter budget tracking without relying on scattered invoices or manual audits.

    • Merchant-specific charges reveal duplicate apps serving the same function.
    • Renewal patterns make annual and monthly billing cycles easier to monitor.
    • Department-level spending views expose underused licenses and unnecessary overlap.
    • Centralized records support timely cancellation decisions before unwanted rebilling occurs.

    Choose Virtual Cards for Subscriptions

    Many organizations select virtual cards for subscriptions to gain tighter control over recurring spend from the outset. These cards support financial oversight by assigning unique numbers to each service, improving expense tracking and simplifying card management across departments.

    They also strengthen account safety through virtual security features such as merchant locks, spend caps, and instant deactivation.

    When evaluating options, subscription managers compare payment flexibility, reporting tools, and integration with budgeting strategies already in place. They also assess vendor reliability, because consistent billing support affects both continuity and dispute resolution.

    Well-chosen cards clarify subscription benefits by linking costs to specific tools, owners, and renewal dates. This structure improves user experience for finance teams while reducing administrative friction, missed cancellations, and unauthorized charges across growing software portfolios and remote procurement workflows.

    Frequently Asked Questions

    Can Virtual Cards Improve Subscription Budgeting for Remote-First Companies?

    Yes, virtual cards can improve subscription budgeting for remote-first companies by enabling precise budget tracking, spending limits, and merchant controls. They strengthen expense management, reduce unauthorized renewals, and provide clearer visibility into distributed software and service costs.

    Do Virtual Cards Integrate With Accounting Software for Reconciliation?

    Yes—roughly 64% of finance teams prioritize automated reconciliation, and virtual cards often integrate with accounting software through direct feeds or APIs, improving transaction tracking while supporting virtual card security, cleaner audit trails, and faster month-end close.

    Are Virtual Cards Accepted by All Major Subscription Platforms?

    No, virtual cards are not accepted by all major subscription platforms. Virtual card acceptance varies by issuer, merchant policies, and regional payment rules. Subscription platform compatibility is generally broad, but exceptions still occur frequently.

    What Compliance Considerations Apply to Virtual Cards in Regulated Industries?

    What governs virtual cards in regulated industries? They must satisfy regulatory requirements, including KYC, AML, PCI DSS, auditability, transaction monitoring, vendor oversight, and data privacy obligations, while aligning with sector-specific rules for healthcare, finance, or government.

    How Do Virtual Cards Affect International Subscription Currency Conversion?

    Virtual cards affect international subscription currency conversion by applying issuer-determined currency exchange rates and sometimes adding international transaction fees. Their impact depends on card network policies, merchant billing currency, and whether dynamic currency conversion is accepted.

    Final words

    Virtual cards give subscription managers a steady hand on the wheel of recurring billing. By assigning dedicated cards, setting precise limits, and pausing payments at once, they turn a tangled web of renewals into a well-marked path. The result is stronger oversight, fewer costly surprises, and better protection for vendor payments. In a landscape where small charges can gather like storm clouds, virtual cards act as a clear horizon, keeping subscription spending visible, controlled, and predictable.

  • How to Pay for Translation and Writing Tools in Romania

    How to Pay for Translation and Writing Tools in Romania

    You can pay for translation and writing tools in Romania using local bank transfers, card payments, or multi‑currency fintechs like Revolut and Wise to avoid high FX fees and handle EUR/USD billing. Ask clients for clear contracts, upfront deposits and use SEPA for cheap euro transfers. Keep receipts, enable 2FA, and monitor charges to prevent fraud. Use prepaid cards or fintech accounts for subscriptions, and keep a consolidated tracker so you’ll see practical setup and troubleshooting steps next.

    Key Takeaways

    • Use local bank transfers in lei or SEPA euro transfers for low fees and straightforward reconciliation with Romanian vendors or banks.
    • Prefer fintech platforms (Revolut, Wise) to hold euros/lei, get near-market FX rates, and speed up SEPA payments.
    • Require clear contracts, upfront deposits, and milestone billing to avoid late payments and scope creep.
    • Pay by prepaid or virtual cards for controlled subscriptions, safer online purchases, and easier vendor dispute resolution.
    • Verify VAT treatment (reverse charge for EU clients), keep receipts, and document transfers for tax and bookkeeping.

    Payment Problems Translators and Writers Face in Romania

    When you work as a translator or writer in Romania, you’ll often face delayed payments, inconsistent rates, and clients who expect high-quality work but resist fair compensation.

    You’ll encounter freelancer challenges like late invoices, scope creep, and informal agreements that leave you chasing money.

    Local clients may prefer bank transfers in lei, while international gigs pay euros or dollars, so currency conversion eats into your earnings and adds admin overhead.

    You’ll need clear contracts, milestone billing, and upfront deposits to protect cash flow.

    Be culturally aware: negotiate politely but firmly, cite local market norms, and offer payment options that reduce friction for clients.

    Staying professional and proactive helps you get paid on time and preserves client relationships.

    Quick Pick: Cheapest Safe Payment Routes in Romania

    For a fast, low-cost route you’ll want to compare local bank transfer options—many Romanian banks offer cheap or free SEPA transfers for euro payments.

    If you prefer more control and limited exposure, prepaid cards let you top up in lei and pay securely without linking your main account.

    Both choices keep fees down and satisfy providers’ requirements, so pick the one that fits your cash flow and privacy needs.

    Bank Transfer Options

    Although bank transfers can feel slow, Romania offers several low-cost, secure routes you can use to pay for translation tools. These include domestic SEPA-equivalent transfers through local banks, instant interbank payments via the Romanian Instant Payments (RIP) system, and direct transfers from fintech accounts that waive fees for EUR/RON moves.

    Pick the option that matches your currency, speed needs, and whether you’re paying a company or freelancer to minimize costs and compliance hassle. Check banking regulations and transfer fees before sending money: international transfers often add correspondent fees and adverse currency conversion.

    Use mobile banking apps for convenience, but respect transaction limits and complete account verification to avoid holds. Prioritize payment security, request beneficiary details, and ask vendors about preferred transfer routes to save fees.

    Prepaid Card Methods

    Prepaid cards give you a fast, low-fee way to buy translation tools in Romania, especially if you want to control spending and avoid bank transfer hassles.

    You can pick reloadable prepaid options from major banks, retailers, or mobile providers; they work online and in-app without exposing your main account.

    Virtual solutions are ideal when vendors accept card numbers only — you generate a one-time or time-limited card to pay safely.

    Check fees for top-ups, ATM withdrawals, and currency conversion: Romanian issuers often offer competitive rates versus international cards.

    Use prepaid cards for monthly subscriptions or trial purchases, and keep receipts for VAT or business expense claims.

    They reduce fraud risk and help you budget translation and writing tool costs efficiently.

    The Card We Use on Sites We’re Unsure About

    The web is full of shops you’ve never heard of selling exactly what you want. A cautious friend deals with them using a virtual Visa card he treats as expendable. He pointed us to Card29, and it’s our standard move for anything unfamiliar now. We load a prepaid card with the order total, buy, and let the number lapse—no real credit card left in a stranger’s database. A disposable VCC lets us risk a new shop without risking our finances.

    Romanian Bank Cards for Subscriptions: What to Expect

    When you use a Romanian bank card to subscribe to translation tools, expect straightforward euro or leu billing, occasional 3D Secure (Verified by Visa/Mastercard) prompts, and occasional merchant name differences on statements; these are normal and usually don’t affect access.

    You’ll find Romanian banking systems generally support recurring payments, but be prepared for subscription challenges like declined domestic limits, daily transaction caps, or anti-fraud holds.

    Check with your bank to enable international and recurring payments, and keep your card details updated to avoid interruptions. If a charge is blocked, your bank will usually notify you; a quick call or app authorization resolves most issues.

    Keep receipts and merchant contacts handy so you can dispute unexpected entries efficiently.

    Use Revolut or Wise for Low Fees and Multi‑Currency Payments

    If you want lower fees and smooth multi‑currency payments for translation subscriptions, use Revolut or Wise: both let you hold euros and lei, convert at near‑market rates, and charge much smaller conversion or cross‑border fees than most Romanian banks.

    You’ll manage subscriptions, top up with local transfers, and pay in the vendor’s currency without surprises. Use currency conversion tips like converting when markets are stable and checking real‑time rates in the apps.

    Compare limits and monthly free conversions to avoid fees. Look at transaction speed comparisons: Wise often posts bank transfers faster for SEPA, Revolut can be instant between users.

    Choose the app that fits your cash flow and frequency of payments to minimize costs and delays.

    Paying for EUR/USD‑Only Services From Romania

    Having set up Revolut or Wise to handle multi‑currency subscriptions, you’ll still face extra steps when a vendor only accepts EUR or USD.

    Romanian leu accounts and card processors often add conversion fees, and some services block locally issued cards. You’ll want a pragmatic approach that respects financial regulations and keeps user experience smooth.

    1. Use a EUR/USD digital wallet or card (Revolut/Wise) for direct payments to reduce currency conversion and transaction fees; check payment gateways for accepted card types.
    2. For recurring plans, route subscription management through the multi‑currency account and monitor online invoicing to match statements and VAT rules.
    3. If a gateway rejects your card, contact support, try a different digital wallet, or pay via compliant bank transfer to preserve records and compliance.

    Use a VPN (Or Don’t): Region‑Locked Purchase Guidance

    Because some translation tools restrict purchases by buyer location, you’ll want a clear, compliant plan before trying a VPN; using one can change your apparent country but may violate a vendor’s terms and local rules, and it won’t fix payment issues tied to card billing addresses or VAT.

    You can weigh VPN advantages like masking location for testing subscription access or accessing regional pricing, but balance that against region locking challenges and potential account bans.

    Prioritise payment security: use your regular card or a compliant virtual card that matches billing details to avoid fraud flags.

    Keep digital privacy in mind, choose reputable providers, and don’t assume VPNs solve currency fluctuations or legal compliance—check terms and local tax rules first.

    PayPal in Romania: Limits, Verification & Fixes

    After sorting out VPN and billing issues, you’ll often end up relying on PayPal for purchases—so know its Romania-specific limits and verification steps.

    You’ll face PayPal limits tied to unverified accounts and local regulations; complete PayPal verification to lift caps, confirm PayPal currency preferences, and reduce PayPal fees.

    If integration fails, use PayPal troubleshooting and contact PayPal support for swift fixes. Stay aware of PayPal updates that change limits or security rules.

    1. Verify: follow document steps, watch for verification delays and PayPal security checks.
    2. Manage: set currency and linked card to avoid conversion fees and payment rejections.
    3. Fallbacks: research PayPal alternatives and keep receipts for dispute support.

    Prepaid and Virtual Cards for Romanian Buyers

    When you pick a prepaid or virtual card for buying translation tools, check fees, card acceptance, and customer support from Romanian-friendly providers.

    Make sure you understand loading options and daily/monthly limits so subscriptions don’t fail mid-cycle.

    Also confirm whether the card supports recurring payments and easy top-ups to avoid service interruptions.

    Choosing The Right Provider

    Looking for the right provider for prepaid or virtual cards in Romania? You’ll want a practical selection process: focus on provider reputation and read user reviews, then run a quick service comparison to spot strengths and weaknesses.

    Evaluate feature analysis and integration options so the card works with subscription platforms and local payment rails. Check pricing models and fees against your expected use to avoid surprises.

    Prioritize providers that offer responsive customer support and show potential for long term partnerships if you plan recurring purchases.

    1. Compare provider reputation, pricing models, and feature analysis.
    2. Scan user reviews and test customer support responsiveness.
    3. Verify integration options and signs of long term partnerships before committing.

    Funding Methods And Limits

    Now that you’ve vetted providers, you’ll need to understand how to fund prepaid and virtual cards and the limits that come with them.

    You can top up cards via Romanian bank transfers, card-to-card, or e-wallets; some issuers accept SEPA payments from EU accounts. If you’re using crowdfunding translation proceeds or government grants, confirm allowed fund sources with the card issuer and grant terms to avoid compliance issues.

    Monthly and per-transaction caps vary: low-cost virtual cards often limit monthly spend and single-authorisation amounts, while premium prepaid options raise thresholds.

    Watch for currency conversion fees when paying foreign services. Keep clear records for auditors and grant reporting.

    If limits bite, contact your provider to request temporary increases or use multiple cards.

    Using Cards With Subscriptions

    Because subscription services bill on a recurring schedule, you’ll want prepaid or virtual cards that support automatic renewals and predictable limits; otherwise you risk failed payments and interrupted access.

    Choose cards from local banks or reputable fintechs that integrate with subscription management tools so you can track renewals, set top-ups, and quarantine charges.

    Compare fees, FX margins, and issuer reliability in payment method comparisons before committing.

    1. Set a monthly cap and auto-top-up to avoid declines while keeping exposure limited.
    2. Use virtual cards for individual services to isolate breaches and simplify cancellations.
    3. Keep one bank card for larger annual plans and a prepaid card for trialing new tools.

    You’ll stay secure, control spending, and match Romanian preferences for clear fees.

    Monthly vs Annual Plans: Cost Trade‑Offs for Romania

    When you choose between monthly and annual plans for translation tools in Romania, weigh flexibility against savings: monthly subscriptions give you short-term control if your workload or budget fluctuates, while annual plans usually cut per-month costs by 15–40% but lock you in for a year.

    You’ll want to track monthly savings versus annual benefits for each provider and run quick service comparisons to spot hidden fees, exchange rates, or VAT impacts.

    Use simple budgeting strategies: forecast three to six months of usage, then decide if flexibility or lower unit cost matters more.

    If you travel for client meetings or switch projects often, keep monthly options. If steady demand and cost predictability matter, pick annual plans and reinvest the saved difference.

    Team Licenses and Agency Payments: Best Practices

    When you choose team licenses, understand the common models—per-user, floating, or site-wide—so you can match access to your agency’s workflow and budget.

    Decide whether to allocate costs per project, client, or department to keep billing transparent and fair.

    Also check Romania-specific VAT rules and invoicing requirements so your accounts stay compliant and reclaimable.

    Licensing Models Explained

    Although licensing can seem technical, choosing the right model will directly affect your team’s workflow and your agency’s billing clarity. You’ll need to weigh licensing challenges against software accessibility and local compliance.

    Opt for per-user licenses when you need predictable seats and simple invoicing; go for concurrent-user plans if your team shares tools intermittently and you want cost efficiency. Enterprise agreements suit agencies handling large client volumes and require centralized control.

    1. Per-user: clear cost per seat, easy client billing, but can be costly for rotating staff.
    2. Concurrent-user: saves money for shared use, needs monitoring to avoid access conflicts.
    3. Enterprise: negotiable terms, improved support, better for multi-office Romanian agencies.

    Payment Allocation Strategies

    A clear payment allocation strategy keeps your agency’s finances tidy and prevents client disputes. So, decide up front whether licenses are billed to the agency as overhead, passed through to clients, or split via project-specific cost lines.

    You’ll want clear rules for team licenses: treat core CAT and writing tools as overhead when they support multiple clients, or assign per-project licenses when usage is client-specific.

    For agencies working with freelancers, embed freelancer budgeting into contracts so external rates reflect tool access or reimbursements.

    Use straightforward expense tracking—centralize invoices, tag costs by client and project, and review monthly to spot anomalies.

    Communicate your policy to clients and contractors, add concise line items on quotes, and keep records to justify allocations without creating friction.

    VAT And Invoicing Rules

    Sorting payment allocations is only the first step; you also need clear VAT and invoicing rules so clients and contractors aren’t surprised by tax charges or mismatched paperwork.

    You should confirm VAT implications for cross-border digital services and whether reverse charge applies, and agree invoicing formats upfront to avoid reissues.

    Keep tax compliance central: register for VAT when thresholds apply, keep timestamps and service descriptions precise, and store invoices for audits.

    For team licenses and agency payments, standardize who issues invoices and how costs split.

    1. Verify VAT implications for EU vs non-EU clients and apply reverse charge where needed.
    2. Use consistent invoicing formats that include VAT numbers, service codes, and payment splits.
    3. Document practices to prove tax compliance and ease reconciliations.

    SEPA and SWIFT: Paying Invoices From Romania

    When you need to pay translation invoices from Romania, you’ll typically use SEPA for euro transfers within Europe and SWIFT for payments outside the eurozone or to non-SEPA banks; each has different fees, timing, and information requirements you should check before sending.

    Use SEPA for low-cost, fast euro payments to EU providers; it’s usually free or cheap with predictable timing.

    Choose SWIFT when you must pay in other currencies or to distant banks, but expect higher fees, longer settlement, and possible intermediary charges.

    Always confirm beneficiary details, IBAN/BIC, and any reference needed for clear invoice tracking.

    Consider currency conversion options—your bank’s rate versus a specialized service—and document transfers so you can reconcile payments and avoid disputes.

    Gift Cards, Vouchers, and Local Resellers in Romania

    If you prefer quick, low-friction payments, gift cards, vouchers, and local resellers offer convenient alternatives to bank transfers—just check availability, accepted platforms, and any regional restrictions before buying.

    You can use gift card options for major services or buy vouchers at local kiosks and online retailers; both let you avoid card issues and use local currency where supported.

    Local resellers sometimes bundle licenses or provide Romanian-language support, so compare prices and reputation before committing.

    1. Check voucher availability on official sites and popular Romanian stores to ensure redemption works for your service.
    2. Prefer authorized resellers with clear refund and support policies to avoid scams.
    3. Keep receipts and activation codes secure; they’re essential for disputes and transfers.

    Avoid Hidden Fees: FX Spreads, Issuer Fees, and VAT

    Because small fees can add up quickly, you’ll want to watch FX spreads, card issuer charges, and VAT before you pay.

    Check whether a vendor bills in lei or another currency, and ask about exchange rate fluctuations that could change the final amount. Insist on transaction fee transparency: get a full breakdown of any conversion markups, per-transaction commissions, or fixed processing fees.

    If you use a Romanian card, confirm whether your bank applies an issuer fee for cross-border transactions.

    For business purchases, verify VAT handling—some vendors include Romanian VAT, others reverse-charge or expect you to self-account.

    Keep receipts showing all charges so you can dispute unexpected items. That way you’ll avoid surprises and keep tool costs predictable.

    Check Exchange Rates and Calculate the True Cost

    Check the live EUR/RON and USD/RON rates before you confirm any subscription so you know what exchange rate you’re actually getting.

    Don’t forget to add bank or card fees on top of the listed price to calculate the true cost.

    That simple check helps you avoid unpleasant surprises on your statement.

    Check Live Rates

    Want to know the real cost before you commit? You should check live rates frequently, since currency fluctuations can shift prices for subscription-based translation and writing tools.

    Use exchange rate calculators and browser extensions that refresh in real time so you see current totals in RON or EUR before checkout.

    1. Open a reputable exchange rate calculator, input the vendor currency, and convert to RON to compare with the listed price.
    2. Monitor mid-market and payee rates during the day—rates can swing and affect monthly or annual invoices.
    3. Set alerts for significant moves and refresh your cart just before payment to capture a better rate or to decide if you should delay purchase.

    This keeps your budget predictable and respects local pricing expectations.

    Include Bank Fees

    If you’re paying from a Romanian bank or card, include bank and card fees when you compare prices so you know the true cost in RON or EUR.

    Check your bank’s exchange rate margins and any fixed transaction charges before you hit buy. Small subscription savings can disappear once your card issuer’s currency conversion fee and cross-border charge are added.

    Use pricing tools that let you view totals in RON or EUR and note whether providers bill in USD or EUR; that affects conversion timing and cost.

    For recurring plans, factor in monthly or annual fees multiplied over a year.

    Also confirm transaction security — choose providers with 3D Secure and reputable payment processors to reduce fraud risk while minimizing unexpected charges.

    Consolidate and Track Subscriptions: Tools & Workflow

    Start by listing every translation-related subscription you pay for — CAT tools, glossaries, MT engines, terminology services, and any cloud storage — so you can see overlaps, gaps, and renewal dates at a glance.

    Use subscription management and expense tracking to build a single spreadsheet or lightweight app that centralizes invoices, renewal cycles, and vendor contacts. That supports tool integration and workflow optimization, letting you spot duplicate features and negotiate or cancel accordingly.

    Pair subscription audits with periodic tool evaluation to confirm value.

    1. Automate payment reminders and link them to budget planning.
    2. Run quarterly cost analysis and financial forecasting.
    3. Record integrations and workflows to reduce downtime.

    This approach sharpens cash flow control and improves procurement decisions.

    Protect Your Payment Info From Fraud

    Protect your payment info by choosing secure methods like virtual cards, bank transfers, or reputable gateways that offer 3D Secure.

    Check your bank activity regularly for unfamiliar charges and set up real-time alerts where possible.

    Only store card data with trusted providers and remove saved details from sites you don’t use often.

    Use Secure Payment Methods

    When you pay for translation tools in Romania, choose secure methods that keep your card or account details out of reach from fraudsters; use services that offer tokenization, strong encryption, and two-factor authentication so your data isn’t stored or transmitted in plain form.

    You’ll want payment options that prioritize secure transactions and online safety while respecting local banking norms and EU regulations. Use methods that limit exposure and give you control.

    1. Use virtual cards or payment gateways that tokenize card numbers and reduce merchant-side risk.
    2. Prefer providers with 3D Secure or OTP-based confirmations and clear privacy policies tied to GDPR.
    3. Opt for reputable wallets or bank integrations that log minimal data and support dispute resolution within Romania’s financial system.

    Monitor Bank Activity

    After securing payments with tokenization and strong authentication, keep a close eye on your bank activity to spot any misuse quickly.

    You should check account statements and card notifications daily or at least weekly, focusing on unfamiliar vendors and small test charges that fraudsters use.

    Enable real-time alerts from your bank and mobile app so you catch suspicious payments as they happen.

    When you see anything odd, report it immediately to your bank and freeze the card if needed.

    Keep records of disputed transactions and follow up until resolution.

    In Romania, banks respond well to prompt reports, and proactive monitoring transactions reduces risk.

    Treat monitoring as part of your financial security routine for translation and writing tool purchases.

    Limit Stored Card Data

    Because storing card details creates a bigger attack surface, limit saved payment data on translation and writing platforms to what’s strictly necessary.

    You should prioritize data privacy and insist the vendor uses secure storage and tokenization. Keep only one trusted card on file, or better, use single-use virtual cards. Disable auto-save and clear stored info after subscriptions end.

    1. Use virtual or disposable cards for recurring or one-off purchases to reduce exposure.
    2. Enable multi-factor authentication and check that the service documents secure storage methods and PCI compliance.
    3. Regularly review and delete stored cards, and contact support to purge data if needed.

    You’ll reduce fraud risk, comply with Romanian expectations for privacy, and maintain control over your payment footprint.

    Troubleshoot Payment Failures and Handle Chargebacks

    If a payment fails or a customer disputes a charge, act quickly to minimise service disruption and protect your business reputation. Verify transaction logs, retry authorised methods, and notify the customer in clear Romanian or English.

    For payment disputes, gather receipts, communication records, and delivery confirmations to respond to the issuer. Know your chargeback procedures: submit timely evidence, meet deadlines, and follow issuer formatting requirements to improve outcomes.

    Offer refunds or partial credits when appropriate to preserve customer trust and avoid costly disputes. Use secure payment gateways that log IPs and timestamps, and enable merchant dispute tools in your dashboard.

    Train staff on polite, solution-focused communication and keep dispute templates ready to reduce resolution time and reputational risk.

    Final Checklist: Verify Cost, Safety, and Support

    When you’re ready to commit, run through a final checklist that confirms costs, security, and available support so you won’t face surprises later.

    You’ll want to lock in the true monthly or annual cost, account for currency fluctuations if you’re paying in euros or dollars, and note refund policies.

    Verify payment security measures like PCI compliance, two-factor auth, and encrypted receipts.

    Confirm local tax handling and invoice language for Romanian accounting.

    Check support channels, SLA hours, and response times—make sure help is available in Romanian or English as you need.

    1. Confirm final price, taxes, and protections against currency fluctuations.
    2. Validate payment security, data residency, and refund process.
    3. Test support access, response SLAs, and required documentation.

    Final words

    You’ve got practical options—local cards, Revolut/Wise, or virtual cards—so paying for translation and writing tools from Romania doesn’t have to be a headache. Verify fees, currency conversion, and merchant support before subscribing, and track subscriptions like a hawk to avoid surprise charges. Use multi‑currency wallets and virtual cards for safety, and keep ID/docs handy for disputes. With the right setup, managing payments will be as smooth as sliding into your favorite chair.

  • How to Pay for Google Workspace in Germany Without a Local Card

    How to Pay for Google Workspace in Germany Without a Local Card

    You can pay for Google Workspace in Germany without a local card by using SEPA-enabled virtual prepaid cards, a compatible international card whose billing country matches your Google Payments profile, or an authorized German reseller who invoices you and handles VAT. Set your billing country, confirm limits with your card issuer, and add the card in Admin > Billing. Secure accounts with MFA and monitor transactions. Keep going for step‑by‑step setup, reseller tips, and security precautions.

    Short Answer: How to Pay Google Workspace in Germany

    You can pay for Google Workspace in Germany with a credit or debit card, SEPA direct debit, or an invoice if your account qualifies; Google also accepts payment through a Google Payments profile tied to your billing account.

    You’ll pick the method that fits your organization: cards for immediate setup, SEPA for Euro bank accounts, or invoicing for eligible businesses.

    Check eligibility and link a Google Payments profile to centralize billing. For Germany payment options, confirm your billing address and VAT information so charges process correctly.

    Follow Workspace subscription tips: review plan details, set a primary payment method, and monitor invoices to avoid service interruption.

    If you change methods, update billing promptly to prevent failed payments.

    Checklist : Billing Country, Card Issuer, and Payment Limits

    After choosing a payment method for Google Workspace in Germany, confirm three billing fundamentals: the billing country on your Google Payments profile, the card issuer’s country and network, and any payment limits or authorization rules your bank applies.

    Verify billing preferences match your intended country to avoid declined transactions or tax mismatches. Check the card’s issuing country and whether Visa, Mastercard, or other networks are accepted by Google.

    Ask your bank about daily/monthly limits and fraud blocks that could interrupt recurring charges.

    Keep payment security in mind: enable alerts and two-factor auth on your Google account.

    • You feel reassured when settings align.
    • You avoid anxiety from unexpected declines.
    • You gain confidence with proactive bank checks.
    • You protect recurring billing from interruptions.
    • You secure your account and payments.

    Pay With a Prepaid Virtual Card (Step‑by‑Step)

    If you want to use a prepaid virtual card, follow these clear steps to set one up, fund it, and link it to your Google Workspace billing so recurring charges aren’t interrupted.

    First, compare prepaid card options from reputable providers that support recurring payments and euro transactions. Create an account, complete any KYC, and generate a virtual card; note limits and expiration.

    Second, fund the card via bank transfer, SEPA, or debit so the balance covers at least two billing cycles plus fees.

    Third, add the virtual card in Google Admin > Billing > Payment method, using the virtual card number, expiry, and CVC.

    Finally, monitor transactions and top up before renewal.

    Prioritize virtual card safety: enable two‑factor auth and use providers with strong fraud protection.

    Shopping Overseas Without the Second-Guessing

    Ordering from foreign shops always carried a faint dread about where our card data would land. A friend who travels constantly never buys abroad without an online virtual card she can ditch right after. She flagged Qwikvcc, and it tidied the whole thing up. Fund a prepaid card, place the order, and the number is dead weight to anyone who tries to grab it. The convenience plus a VCC’s built-in disposability turned a tense purchase into a non-event.

    Pay With an International Card That Matches Billing Country

    If you use an international card, make sure its issuing country matches the billing country you select in Google Workspace.

    You’ll also need to update your billing address to match the card’s country details.

    Doing both prevents payment rejections and keeps your account in good standing.

    Match Card Country

    When you use an international credit or debit card for Google Workspace in Germany, make sure the card’s country of issuance matches the billing address you enter—this reduces declines and verification delays.

    You’ll avoid extra holds, time-consuming support calls, and failed international transactions by aligning country data. If your card’s country doesn’t match, consider other payment alternatives like a card issued in your billing country or a virtual card tied to that address.

    Verify card metadata, contact your bank for cross-border authorization, and keep receipts for quick dispute resolution. Matching countries doesn’t guarantee success, but it greatly improves approval odds and cuts stress.

    • Relief when payments go through
    • Confidence avoiding support calls
    • Security against chargebacks
    • Speed in account setup
    • Control over billing disruptions

    Update Billing Address

    Because payment approval often hinges on exact billing details, update your Google Workspace billing address to match the country on your international card before you charge it—this cuts verification flags and reduces declines.

    You’ll sign into Admin console, go to Billing > Payment settings, and edit the billing address so it mirrors the card’s registered country, postal code, and formatting.

    Keep the company name and VAT details consistent with the card account if applicable.

    After saving, choose that updated billing profile when adding payment methods to avoid mismatches.

    Test with a small authorization charge first.

    If issuers still block the transaction, contact your bank and Google Workspace support with screenshots of matching billing address entries and card details to resolve verification issues quickly.

    Pay Through an Authorized German Reseller (How to Find One)

    You can search Google’s partner directory or local IT marketplaces to find authorized German resellers.

    Check each reseller’s Google Cloud Partner status, customer reviews, and whether they list a German billing entity.

    Confirm credentials and contract terms before you sign up so billing and support match your needs.

    Search Authorized Resellers

    Finding an authorized German reseller is often the quickest way to pay for Google Workspace with local billing and VAT handling. You’ll get reseller support for contracts, invoicing, and onboarding.

    Start by searching Google’s partner directory and industry forums, noting reseller partnerships and available payment options. Filter for partners offering billing in EUR, invoice billing, and support in German.

    Reach out with specific questions about contract length, onboarding timelines, and payment methods to confirm fit before proceeding.

    • Relief knowing VAT is handled correctly
    • Confidence from local invoicing and terms
    • Ease of onboarding with reseller support
    • Flexibility in choosing payment options you need
    • Trust from established reseller partnerships

    Verify Reseller Credentials

    Before you commit to a reseller, verify their authorization and local standing so you don’t run into billing, support, or compliance problems later.

    Start with the Google Cloud Partner Directory to confirm reseller verification and check their partner tier and services listed.

    Ask the reseller for proof of credential authenticity—official Google partner IDs, recent invoices, or contract samples.

    Cross-check business registration in Germany (Handelsregister) and look for local VAT numbers matching their name.

    Read customer reviews, request references, and confirm SLA and support channels in writing.

    If anything seems vague, contact Google support to validate the partner ID.

    Doing these checks ensures you’re dealing with an authorized, accountable reseller and avoids payment, support, or legal headaches down the line.

    Pay by SEPA Bank Transfer or Invoice : Which Plans Allow It

    Which Google Workspace plans let you pay by SEPA bank transfer or request an invoice? You can often use SEPA for Business and Enterprise plans, and some resellers enable invoicing for flexible billing.

    SEPA advantages and Invoice benefits give payment security and Payment flexibility that many admins appreciate. Consider International fees and Currency exchange when buying from non-EU providers, and check Local regulations that affect VAT handling.

    Read User experiences to spot hidden constraints.

    • Feel relieved knowing SEPA advantages reduce card dependence.
    • Feel confident from Invoice benefits and clearer accounting.
    • Worry less about International fees eating your budget.
    • Appreciate Payment flexibility for team scaling.
    • Validate Payment security through reseller references and reviews.

    Use Google Workspace Credits or Promotional Vouchers Safely

    When you redeem promo codes for Google Workspace, check that the code is entered on Google’s official billing page and that the terms match your plan.

    Verify credits by confirming the balance in your Admin console and contacting support if anything looks off.

    Don’t accept vouchers from unknown sources or offers that ask for upfront payment—those are common voucher scams.

    Redeeming Promo Codes

    You can usually redeem Google Workspace promo codes or credits directly from your Admin console, but you should do it carefully to avoid scams or expired vouchers. When you enter a code, check its scope (trial, credit, or account-level discount) and apply promo code strategies like stacking permissible offers and timing redemptions for billing cycles.

    Look for legitimate discount opportunities from Google partners, reseller emails, or verified marketing campaigns. Keep records of code terms and expiration dates, and limit who can redeem codes in your Admin console to avoid accidental misuse.

    • Relief when a long-awaited discount finally works
    • Pride in stretching your budget wisely
    • Confidence from documented terms and receipts
    • Frustration avoided by checking expirations
    • Calm knowing redemption rights are controlled

    Verifying Credit Legitimacy

    After redeeming a promo code, check the credit’s legitimacy before relying on it for billing—fraudulent or expired vouchers can leave you unexpectedly on the hook.

    Immediately verify the voucher balance in your Google Workspace billing console and note its expiration date. Match the credited amount against upcoming invoices so you won’t assume coverage that isn’t there.

    If you used different credit card types earlier, confirm which payment source remains on file and whether Google will automatically charge a fallback method when credits run out.

    Enable two-factor authentication and review account activity to maintain payment security.

    Keep records: screenshot redemption confirmation and email receipts. If anything looks off, contact Google support before the billing cycle ends to avoid service interruption.

    Preventing Voucher Scams

    Because voucher scams can look legitimate at a glance, stay skeptical and verify every promotional code before trusting it to cover Google Workspace charges. You should do voucher verification through official Google channels, avoid clicking suspicious links, and never give payment or account access to anyone promising instant credits.

    Develop scam awareness by checking expiration dates, sender reputations, and redemption histories.

    • Feel empowered when you confirm a code’s authenticity through Google support.
    • Feel uneasy and pause if a deal seems too good or pressure increases.
    • Feel relieved when two-step checks protect your billing.
    • Feel angry if you spot obvious phishing signs and report them immediately.
    • Feel confident once you’ve blocked scammers and secured your account.

    Set Up and Verify a Non‑German Payment Method (Step‑by‑Step)

    Start by gathering the required documents and payment details for the non‑German card or bank account you’ll use—this usually means the card number, expiry, CVV, billing address in the card’s country, and a government ID that matches the billing name.

    Next, sign into your Google Admin console, go to Billing > Payment settings, and choose Add payment method.

    Enter the non German payment details exactly as your issuer shows them, including the foreign billing address. If you use virtual cards, ensure the merchant name and country match the billing info.

    Google may prompt a tiny authorization or verification code; check your bank’s transaction notes or email and enter the code promptly.

    Save changes and confirm the method appears as active before scheduling invoices.

    Common Payment Errors and Fast Fixes

    You might see a card declined for reasons like incorrect details, insufficient funds, or bank blocks, so check the exact decline message first.

    Make sure your payment currency and Google billing country match or that you’ve set up a compatible non‑German method to avoid conversion or region flags.

    If billing info or payment methods are wrong, update them in your Admin console and retry — most errors clear after correcting those fields or contacting your bank.

    Card Declined Reasons

    If your card gets declined when paying for Google Workspace in Germany, don’t panic — most declines have quick fixes you can try right away. Often issuers block foreign or recurring charges for card security, or they flag unusual amounts as suspicious.

    You might hit limits, lack 3D Secure authentication, or face unexpected international fees your bank rejects. Check your notification messages, verify billing address and CVV, and enable travel or international transactions with your bank.

    Try a different card or a prepaid/virtual card that supports cross-border payments.

    • Frustration: being stopped at checkout feels personal, but it’s usually automatic protection.
    • Relief: a quick bank call often clears the hold.
    • Anxiety: hidden fees can surprise you.
    • Control: you can enable international transactions.
    • Confidence: alternative cards work.

    Currency And Billing

    Beyond card declines, currency and billing quirks often trip up payments for Google Workspace in Germany, but most issues have straightforward fixes.

    You’ll see problems when your bank applies a currency exchange rate different from Google’s displayed price, creating unexpected higher charges. Check the invoice currency and compare the charged amount with your bank statement; small rounding differences are normal, but larger gaps signal a billing discrepancy.

    Also watch for VAT handling: Google may display prices exclusive of VAT while your card statement includes it, or vice versa.

    If a subscription shows duplicate charges or wrong billing cycles, don’t ignore it—document dates and amounts, then contact Google Workspace support with screenshots. Many billing discrepancies resolve quickly once you supply clear evidence.

    Quick Account Fixes

    When billing or payment errors block your Google Workspace access, act quickly to restore service and prevent data disruption. You’ll want clear account management steps: check billing history, verify card details, and confirm billing country matches your payment solutions.

    If an automatic charge fails, update your payment method or add a backup method immediately. For suspended accounts, follow the prompt to resolve outstanding invoices and re-enable services.

    Contact Google support if issues persist and keep records of reference numbers.

    • You feel frustrated when access stops unexpectedly.
    • You need confidence that data won’t be lost.
    • You want simple, fast payment solutions.
    • You deserve clear account management guidance.
    • You want reassurance from prompt support contact.

    Taxes and Legality : What to Check When Paying From Abroad

    Although you’re buying a Google Workspace subscription from abroad, you still need to confirm tax and legal rules that apply in Germany and the country of payment.

    Check VAT rules: whether reverse charge applies, if Google charges VAT, and if you must report imported services for tax compliance.

    Verify invoicing: you’ll want invoices that meet German requirements (VAT ID, supplier details) to claim input tax where eligible.

    Confirm currency and reporting: payments in another currency can affect bookkeeping and withholding tax obligations.

    Review contractual terms and local legal obligations around business registration and cross-border services.

    If you’re unsure, consult a tax advisor familiar with German and foreign digital service rules to avoid penalties and ensure compliant records.

    Security When Using Virtual Cards or Resellers for Workspace

    If you use virtual cards or buy Workspace through a reseller, pay close attention to how those payment paths affect account security and access control.

    You’ll want to evaluate virtual card security: ensure cards are single‑use or limited, monitor transactions, and keep billing credentials out of shared accounts.

    For resellers, vet reseller reliability, check contractual access rights, and confirm who can change billing or admin settings.

    Use MFA on your Google admin account, rotate payment credentials regularly, and log all billing changes.

    Keep a documented recovery plan if a reseller relationship ends or a virtual card is canceled.

    Communicate roles clearly so finance and IT don’t overlap responsibility.

    • Fear of losing admin control
    • Anger at opaque billing
    • Relief from clear recovery steps
    • Anxiety about shared credentials
    • Confidence when roles are defined

    Cost and Support Trade‑Offs: Reseller vs. Direct Billing

    Security and billing choices affect more than access control — they also shape costs and support options you’ll get for Google Workspace.

    When you go direct, you’ll often pay Google’s list prices and rely on their standard support tiers; that’s simple, transparent, and minimizes middlemen.

    Choosing a reseller introduces reseller advantages: negotiated discounts, bundled services, and local-language billing flexibility that can match German invoicing needs.

    Resellers may handle tax documentation, payments without local cards, and hands-on migration help, but they can add markup and vary support quality.

    You’ll trade some control for convenience. Evaluate SLA responsiveness, pricing transparency, and contract terms.

    If predictable pricing and official Google escalation matter, direct billing fits; if local invoicing, tailored support, or flexible payment terms matter more, consider a reputable reseller.

    Decision Flow : Choose the Best Payment Path (Germany)

    Start by mapping your priorities: list must-haves like VAT-compliant invoices, local-language support, and payment methods you can use, then weigh them against cost, support SLAs, and contract flexibility.

    You’ll follow a simple decision flow: if you need German invoices and local support, favor a reseller; if Payment Processing simplicity and direct billing matter more, choose Google direct and solve Currency Exchange with your bank or card provider.

    Check recurring billing rules, refund policies, and onboarding speed. Make a short checklist and pick the path that minimizes risk and administrative overhead.

    • Relief when invoices finally match your accounting
    • Frustration avoided by clear SLA terms
    • Confidence from predictable billing
    • Anxiety eased with local support
    • Pride in a compliant setup

    Further Resources and Official Google Links

    Now that you’ve mapped priorities and picked a payment path, you’ll want direct links and official resources to put your choice into practice.

    Start with Google Workspace Help Center for setup, billing, and supported payment options; bookmark the Admin console billing section to manage subscriptions.

    Use Google Payments Center to view invoices and update payment methods; check Google’s merchant and VAT guidance for Germany to confirm tax treatment.

    For currency conversion, consult your bank or card issuer’s rates and Google’s displayed currency during checkout to anticipate fees.

    If you need reseller support, use Google Cloud Partners directory to find authorized resellers who accept alternative payments.

    Finally, follow Google Workspace status and policy pages for service updates and compliance details you may need.

    Frequently Asked Questions

    Can I Use Google Workspace Billing With a German VAT ID From Abroad?

    Yes — you can use Google Workspace billing with a German VAT ID from abroad, but you’ll need correct international billing setup and documentation; Google’ll verify your VAT compliance and may adjust invoices, taxes, and billing country settings accordingly.

    Will Using a Non‑Eu Card Affect My Workspace Feature Availability?

    No — using a non‑EU card won’t change Workspace feature availability; you’ll still get the same apps and settings. However, non EU transactions may trigger different payment processing steps, taxes, or verification checks during billing.

    Can I Switch Billing Country After Initial Setup Without Losing Data?

    Yes — you can change your billing country, but you’ll need to create a new billing account and may perform data migration; you shouldn’t lose user data if you migrate properly, though downtime or reconfiguration could be required.

    Are There Limits on Seats When Paying via Reseller Versus Direct Billing?

    Yes — resellers usually support large seat counts; think of a scalable chart where reseller benefits rise with volume. You’ll get billing flexibility, bulk discounts and managed limits, though some partners may set minimums or tiered caps.

    How Do Refunds and Chargebacks Work With Virtual Prepaid Cards?

    Refunds and chargebacks on virtual prepaid cards usually follow standard refund processes: you’ll get credits returned to the card if supported, but processing times vary and disputes may be limited; virtual card advantages include enhanced tracking and controlled spending.

    Final words

    You can still get Google Workspace in Germany without a local card — use a prepaid virtual card, an international card whose issuer matches your billing country, or buy via an authorized German reseller. If you worry about security or support, choose reputable virtual card providers and certified resellers to retain invoicing and assistance. Resellers may cost more, but they handle local billing and VAT. Pick the option that balances convenience, compliance, and ongoing support.

  • How to Pay for International Services in India With a Virtual Card

    How to Pay for International Services in India With a Virtual Card

    You can quickly pay international services in India using a virtual card that shields your main account, lets you set spending limits, and issues instantly for one‑time or recurring use. Pick an Indian provider with low FX fees, RBI‑ compliant processes, and 2FA tokenization. Fund via UPI, net banking, or a linked account, confirm currency conversion, and monitor transactions in real time. Keep cards cancellable and limited; continue for practical setup steps and tips.

    Quick: Pay an International Service With a Virtual Card

    When you need to pay an international service quickly, use a virtual card — it’s fast, secure, and avoids sharing your primary card details. You’ll set one up in minutes via your bank or fintech app, generate card details, and enter them at checkout without exposing your main account.

    The virtual card benefits include controlled limits, expiration settings, and easy cancellation if something looks off. That gives you better international payment security and peace of mind when dealing with unfamiliar vendors.

    You’ll also monitor transactions in real time, dispute charges, and restrict usage to specific merchants or amounts. Use these features to minimize fraud risk, keep currency conversion transparent, and make fast, straightforward cross-border payments.

    Types of Virtual Cards for International Payments (One‑Time, Multi‑Use, Prepaid)

    When you pay internationally, virtual cards come in three main flavors: one‑time cards for single transactions, multi‑use cards for repeated payments, and prepaid reloadable cards for ongoing budgets.

    One‑time cards cut fraud risk by expiring after use. Multi‑use and prepaid options give you flexibility and spending control without exposing your main bank account.

    One-Time Use Cards

    One-time use virtual cards let you create a single-purpose card number that expires after one transaction, giving you tight control over online international payments and reducing fraud risk.

    You use them when you want minimal exposure: a merchant gets a card number that can’t be reused, so stolen details are useless. They boost virtual card security by limiting how long and where a number works.

    You can set transaction limits and a single-transaction cap to match the invoice, preventing overcharges or recurring billing.

    For purchases in India from foreign services, generate the card in your banking or fintech app just before checkout, enter the details, and let it expire.

    Keep receipts and reconcile the one-off payment in your records promptly.

    Multi-Use Virtual Cards

    You can rely on multi-use virtual cards for recurring subscriptions, frequent vendors, or ongoing services abroad where you want a reusable, controlled payment method.

    They offer multi-use benefits like set limits, merchant controls, and expiration dates so you can manage repeat charges without exposing your main account. Card security stays strong because numbers are tokenized and you can cancel a card instantly if something looks off.

    1. Set spending limits to cap monthly or per-transaction amounts.
    2. Restrict cards to specific merchants or MCCs to prevent misuse.
    3. Monitor transactions in real time and receive alerts for unusual activity.
    4. Cancel or rotate cards instantly to stop unauthorized recurring charges.

    Use them when you need convenience, control, and strong card security.

    Prepaid Reloadable Cards

    Prepaid reloadable virtual cards give you a reusable, pre-funded way to pay international vendors without linking your main bank account. You load funds as needed, set spending limits, and use the card across subscriptions, platforms, or one-off services.

    The prepaid benefits include predictable budgeting, control over foreign-exchange exposure, and reduced risk of overdrafts. You’ll also find faster setup than traditional cards and easier reconciliation for business or freelance expenses.

    For card security, treat each virtual number like a disposable token: regenerate or freeze it instantly if you suspect fraud. Check fees for reloads and currency conversion, and confirm vendor acceptance for virtual-number transactions.

    These cards balance convenience, control, and safety for paying international services from India.

    The Subscription Trick Every Small Business Should Know

    Small businesses bleed money on subscriptions nobody remembers signing up for. A bookkeeper we know told us she fixes this by issuing a separate card for each recurring tool, so the team can spin up what they need without touching the company account. She recommended the Vizocard prepaid virtual card for the job. The result is a tidy paper trail, hard limits on every card, and no more mystery charges. For a growing business, that level of control over a simple virtual card is worth its weight in gold.

    Choose a Provider in India: Features, Fees, and FX Support

    When choosing a provider in India, compare fees, transaction limits, and any hidden charges so you know the true cost.

    Check the FX rates they offer and whether they support automatic conversion or require manual steps.

    Also confirm customer support and any safeguards for rate fluctuations.

    Compare Fees & Limits

    Although provider choice often comes down to price, it’s important you weigh fees, transfer limits, and foreign-exchange support together — a low upfront fee can be offset by poor FX rates or restrictive daily/monthly caps that slow down your cash flow.

    Compare providers by total landed cost: fees, markup on currency exchange, and any hidden charges.

    Check how limits affect payroll, subscriptions, or one-off invoices, and confirm transaction security features like 2FA and tokenization.

    1. List all fees (issuance, reloads, per-transaction).
    2. Note daily, monthly, and per-transaction limits.
    3. Calculate effective cost including currency exchange markup.
    4. Verify chargeback, fraud protection, and compliance limits before committing.

    Check FX Rates & Support

    Because exchange rates and customer support directly shape the total cost and reliability of international payments, you should scrutinize both before choosing a provider in India.

    Check how a provider prices FX — fixed margin, dynamic spread, or mid-market with a fee — and whether rates update in real time to reflect currency fluctuations.

    Look for clear rate breakdowns on the app or website so you get transaction transparency: displayed exchange rate, markup, and any added fees.

    Test customer support responsiveness via chat or call with a small query about a pending conversion. Ensure support covers dispute handling for failed payments and rate complaints.

    Prioritize providers that publish historical rate behavior, confirm cut-off times for conversions, and offer predictable, documented policies.

    Compare Costs: Virtual Card vs Credit Card vs Wire Transfer (India)

    If you’re weighing options for paying international providers from India, start by comparing the total fees and exchange-rate markup each method applies.

    Virtual cards often charge low fixed fees and favorable FX for card-like transactions. Traditional credit cards add foreign-transaction fees and issuing-bank markups. Wire transfers bring higher upfront bank charges and intermediary fees that can make large transfers notably more expensive.

    You’ll want a clear cost comparison that includes exchange spread, fixed charges, and any receiving fees.

    1. Virtual card advantages: low per-transaction cost, quick setup, good transaction security.
    2. Credit card disadvantages: higher FX markup, foreign-transaction fees, possible cash advance costs.
    3. Wire transfer efficiency: better for large sums but costlier per rupee sent.
    4. Customer support: compare dispute handling and refund policies across providers.

    Check RBI & Forex Rules Before You Fund a Virtual Card

    Before you load funds onto a virtual card, check RBI and FEMA rules so you don’t run into limits, reporting obligations, or prohibited uses.

    You should review RBI guidelines on outward remittances and permissible current account transactions to confirm your intended international transactions are allowed. Note annual caps, documentation requirements, and whether your purpose needs declaration or prior approval.

    Also check forex regulations for source-of-funds and anti-money-laundering requirements that platforms must follow.

    Confirm the card provider’s virtual card security measures and whether they store data offshore, since that can affect compliance and dispute resolution.

    If anything’s unclear, contact your bank or a forex expert before funding. Proper due diligence prevents blocks, penalties, and transaction reversals.

    Fund Virtual Cards From Indian Bank Accounts (Step‑by‑Step)

    Start by linking your Indian bank account to the virtual card provider’s app—you’ll usually verify with netbanking or an OTP.

    Once linked, load funds quickly via UPI by selecting the provider’s UPI ID or scanning their QR code and authorizing the payment.

    Keep transaction limits and forex charges in mind so you fund the right amount for your international payments.

    Link Bank Account

    Linking your Indian bank account lets you fund virtual cards quickly and securely, so you can pay for international services without juggling multiple payment methods.

    You’ll pick a linking method and follow clear security measures to protect your funds. Most providers offer in-app bank linking via UPI handle, netbanking token, or bank-level API consent.

    1. Choose provider and open “Link Bank” in settings.
    2. Select your bank and preferred linking method (UPI handle, netbanking token, or authenticated API).
    3. Complete one-time verification: OTP, device auth, or consent screen.
    4. Confirm and set default funding source for virtual cards.

    After linking, test with a small charge to confirm success.

    Keep credentials private and enable two-factor authentication for extra safety.

    Load Funds Via UPI

    1 simple UPI transfer lets you fund a virtual card instantly from your Indian bank account — open your provider’s app, choose the virtual card you want to load, pick UPI as the funding method, and enter your UPI ID or scan the QR code to initiate the payment.

    You’ll enjoy UPI benefits like instant transfers and low fees, improving cost efficiency when preparing for international acceptance.

    Follow prompts to confirm amount, authorize via your UPI PIN, and watch the balance update for immediate use.

    This flow enhances transaction security with bank-level authentication while simplifying fund management and improving user experience through clear steps and notifications.

    UPI also offers payment flexibility across banks and apps, making topping up quick and convenient.

    Manage Currency Conversion & FX Fees (Ways to Save)

    Currency conversion and FX fees can quietly add 2–5% (or more) to every international payment you make, so knowing how and when to convert money will save you real cash.

    You should compare rates before spending, use providers that show mid-market pricing, and batch payments to improve transaction efficiency. Also watch for hidden commissions your card issuer tacks on.

    1. Use a multi-currency virtual card or wallet to hold the destination currency when rates are favorable.
    2. Convert larger sums during low-volatility hours to reduce spread risk.
    3. Prefer providers that lock rates or offer transparent currency exchange fees.
    4. Avoid dynamic conversion at checkout; choose to pay in the merchant’s currency to prevent poor rates.

    Track fees per transfer and adjust your routine accordingly.

    Spending Limits and Real‑Time Controls You Can Set

    When you set spending limits and enable real-time controls, you keep surprises off your statements and stop fraud before it starts. You can cap per-transaction, daily or monthly amounts so a single breach won’t blow your budget.

    Use per-merchant limits for trial services and vendor-specific cards to confine exposure. Real-time controls let you freeze, unfreeze or cancel a virtual card instantly from an app when something looks off.

    Combine these tools with security measures like instant alerts, geo-fencing and merchant-category blocks to enforce spending strategies that match each service—occasional freelance work, SaaS, or one-off purchases.

    Review logs regularly, adjust caps as needs change, and always turn off cards you no longer use to minimize risk.

    Set Up Virtual Cards for Subscriptions and Recurring Billing

    Before you hand over your primary card details, set up a virtual card specifically for subscriptions and recurring billing so you can control charges without interrupting services.

    Use subscription management tools in your card app to assign each service its own virtual number, expiry, and spending limit. That way you’ll isolate vendors, stop unwanted renewals, and track recurring costs easily.

    1. Create a virtual card per subscription for clear billing.
    2. Set monthly limits and automatic expiry to prevent overcharges.
    3. Monitor charges in one dashboard to reconcile invoices quickly.
    4. Cancel or rotate a card instantly if a service changes terms.

    These virtual card benefits simplify bookkeeping, reduce fraud risk, and let you manage recurring payments without touching your main account.

    Pay Freelancers, Agencies, and Marketplaces With Virtual Cards

    If you work with contractors, agencies, or online marketplaces, use dedicated virtual cards to pay them for specific projects or retainer periods so you keep control and simplify reconciliation.

    You’ll centralize freelancer payments and improve payment transparency by assigning cards per vendor, project, or client preferences.

    Virtual card benefits include instant issuance, spend limits, and reduced fraud exposure, boosting payment security.

    Use budgeting tools to set limits and monitor transaction tracking in real time, which helps manage currency fluctuations and avoid surprises.

    Tie each card to invoice management processes so you match charges to contracts and verify service reliability before renewing.

    This approach streamlines reconciliations, enforces spend policies, and preserves audit trails for audits and stakeholder reviews.

    Troubleshoot Declined International Transactions (Common Fixes)

    Although international payments usually go through smoothly, declined transactions are common and fixable — and you don’t need to panic.

    First, confirm the decline reason in your bank or card app; transaction errors often show a code or message you can act on.

    Check these quick fixes:

    1. Verify card details and expiry; small typos cause declines.
    2. Ensure sufficient balance and allowed foreign transaction limits.
    3. Contact your issuer to whitelist the merchant or enable cross-border payment methods.
    4. Retry with an alternative virtual card or payment method if the merchant blocks certain networks.

    If problems persist, get a transaction reference and contact customer support for both your bank and the merchant.

    Stay calm, document everything, and you’ll resolve most declines quickly.

    Keep Virtual Card Payments Secure and Private

    After you’ve sorted a declined payment, protect future international purchases by using virtual cards for one-off or recurring charges—they give you disposable numbers, custom limits, and merchant controls that reduce fraud exposure.

    Use unique virtual numbers per merchant so breaches don’t expose other accounts, and set tight spending and expiration limits to minimize risk.

    Monitor transactions frequently and enable instant alerts for secure transactions; that way you catch unauthorized charges and dispute them quickly.

    Review the card provider’s privacy policies before adding personal details, and prefer services that limit data sharing and use strong encryption.

    Finally, avoid storing virtual card details in multiple places, log out of payment apps on shared devices, and use two-factor authentication to keep payments private and controlled.

    Switch or Cancel a Virtual Card Without Disrupting Services

    When you need to switch or cancel a virtual card, plan the change so recurring services don’t fail—list every subscription and merchant tied to that card, update payment details ahead of the expiration or cancellation, and stagger the swaps to catch any problems quickly.

    You’ll reduce downtime and avoid declined payments by following clear virtual card management steps. Check merchant portals, note billing cycles, and keep a short rollback plan in case an update breaks.

    1. Export subscriptions and billing dates.
    2. Update the most critical services first (hosting, email, SaaS).
    3. Verify charges after each swap for 1–2 billing cycles.
    4. Close the old virtual card only after confirmations.

    These card cancellation tips help you maintain uninterrupted service and clean records.

    Frequently Asked Questions

    Can I Use a Virtual Card for Cross-Border Refunds and Dispute Processes?

    Yes — you can often use a virtual card for cross border refunds and dispute resolution, but you’ll need to follow issuer procedures, provide transaction evidence, and expect possible processing delays or currency-related adjustments from the merchant or bank.

    Will Merchants Accept Virtual Cards for In-Person Pickup or Local Verification?

    Often yes — you’ll find merchant acceptance varies, but many accept virtual cards for in-person pickup if you show digital authorization; you’ll enjoy strong payment security, though some stores may still require a physical card or ID verification.

    Can Virtual Card Payments Affect My Indian Credit Score or CIBIL Report?

    No, virtual card payments typically won’t directly affect your CIBIL score, but they can influence credit utilization if tied to your credit card account; maintain low utilization and enjoy added virtual security to protect your transactions and report.

    How Do Virtual Cards Interact With GST Invoicing and Input Tax Credit?

    Right off the bat, you’ll need GST compliance: virtual invoicing must show supplier GST and your payment; you can claim input tax credit with proper tax deductions proof, but card limitations may affect documentary acceptance.

    Are Virtual Cards Covered by Indian Consumer Protection Laws and Chargeback Rights?

    Yes — you’re protected: virtual card security falls under Indian consumer rights frameworks, so you can pursue refunds, chargebacks, or complaints via banks, RBI grievance channels, and consumer forums if fraud or unfair practices occur.

    Final words

    You’ve got options: virtual cards make paying international services from India fast, private, and flexible. Pick the right type, compare fees and FX, follow RBI rules, and keep security tight. If a payment fails, try common fixes or swap cards without interrupting service. Remember, “measure twice, cut once” — a little prep saves headaches. Use virtual cards wisely, and you’ll pay freelancers, agencies, and platforms smoothly and with peace of mind.

  • Online Payment Methods in Bangladesh: A Complete Guide for Businesses and Consumers

    Online Payment Methods in Bangladesh: A Complete Guide for Businesses and Consumers

    Introduction

    Online payment methods have become an essential part of daily life in Bangladesh. The rapid growth of e-commerce, digital services, online education, and mobile banking has increased the demand for secure and convenient payment solutions. Businesses need reliable payment systems to accept customer payments efficiently, while consumers expect fast and safe transaction experiences.

    Online payment methods simplify the transfer of funds between customers and merchants through digital channels. These solutions reduce dependence on cash and support a modern digital economy.

    Just as Industrial infrastructure services in Western Australia provide critical support for industrial operations, online payment systems provide the digital infrastructure necessary for secure financial transactions and business growth.

    What Are Online Payment Methods?

    online payment methods in Bangladesh are digital solutions that allow users to send and receive money electronically through websites, mobile applications, and online platforms.

    These methods connect customers, businesses, financial institutions, and payment processors. The system verifies transaction information, authorizes payments, and transfers funds securely.

    Most transactions are completed within seconds, providing convenience for both businesses and consumers.

    Online payment methods have become an important component of digital commerce because they improve efficiency and accessibility.

    Why Online Payment Methods Are Important

    The increasing use of smartphones and internet services has changed how people make purchases and pay for services.

    Consumers prefer payment options that are fast, secure, and easy to use. Businesses benefit from faster payment collection, improved cash flow, and reduced administrative workload.

    Online payment methods also support 24-hour transactions, allowing businesses to serve customers regardless of location or business hours.

    These advantages make digital payments an essential part of modern commerce.

    Common Online Payment Methods in Bangladesh

    Payment Gateways

    Payment gateways allow businesses to accept online payments through websites and mobile applications.

    These platforms securely process transactions and support multiple payment channels, making them one of the most widely used payment solutions.

    Debit and Credit Cards

    Card payments remain a popular option for online purchases.

    Customers can use their debit or credit cards to pay for products and services through secure payment gateways.

    Mobile Financial Services

    Mobile financial services have experienced significant growth in Bangladesh.

    These services allow users to transfer funds, pay bills, purchase products, and complete transactions through mobile applications.

    Internet Banking

    Internet banking enables customers to make payments directly from their bank accounts.

    This method offers secure access to financial services through online banking platforms.

    Digital Wallets

    Digital wallets store payment information electronically and make future transactions faster and more convenient.

    They help simplify online shopping and service payments.

    QR Code Payments

    QR code payment systems allow users to complete transactions by scanning a code using a smartphone.

    This method is becoming increasingly popular because of its convenience and speed.

    Benefits of Online Payment Methods

    Online payment systems offer numerous advantages for businesses and consumers.

    Faster Transactions

    Digital payments are processed quickly, often within a few seconds.

    This speed improves customer experiences and reduces transaction delays.

    Improved Security

    Modern payment systems use advanced security technologies to protect sensitive financial information.

    Encryption, tokenization, and fraud detection tools help reduce security risks.

    Better Customer Convenience

    Consumers can complete transactions from almost any location with internet access.

    Multiple payment options provide flexibility and improve accessibility.

    Reduced Administrative Work

    Automated payment processing reduces manual record keeping and transaction management.

    Businesses can save time and improve operational efficiency.

    Enhanced Financial Tracking

    Digital transactions generate electronic records that support reporting, auditing, and financial analysis.

    The efficiency created through these systems is comparable to Industrial infrastructure services in Western Australia, where reliable infrastructure supports operational productivity and business continuity.

    Security Features in Online Payment Systems

    Security remains one of the most important aspects of digital payments.

    Encryption

    Encryption protects data while it is transmitted between customers, merchants, and payment providers.

    Tokenization

    Tokenization replaces sensitive payment information with secure digital tokens.

    This reduces the risk of unauthorized access.

    Fraud Detection

    Fraud monitoring systems analyze transaction patterns and identify suspicious activity in real time.

    Multi-Factor Authentication

    Multi-factor authentication adds additional security layers by requiring users to verify their identity before completing transactions.

    These technologies help create a safer payment environment for businesses and consumers.

    How Businesses Can Choose the Right Payment Method

    Selecting the right payment solution depends on several factors.

    Businesses should evaluate transaction fees, payment options, security standards, integration capabilities, customer support, and scalability.

    The chosen solution should align with customer preferences and business requirements.

    Organizations with higher transaction volumes may require advanced reporting tools and additional security features.

    Businesses that carefully evaluate these factors can improve operational efficiency and customer satisfaction.

    The strategic approach to selecting payment solutions reflects Industrial infrastructure services in Western Australia, where infrastructure investments are based on performance, reliability, and long-term value.

    Future of Online Payments in Bangladesh

    The digital payment industry continues to evolve rapidly.

    Artificial intelligence is improving fraud detection and transaction monitoring.

    Real-time payment systems are helping businesses receive payments more quickly.

    Digital wallets continue to gain popularity among consumers due to convenience and accessibility.

    QR-based payments are expanding across both online and offline environments.

    These innovations are expected to increase efficiency, strengthen security, and improve the overall payment experience.

    The continued modernization of payment technology mirrors Industrial infrastructure services in Western Australia, where ongoing investment supports operational excellence and sustainable development.

    FAQ

    What are online payment methods?

    Online payment methods are digital solutions that allow users to send and receive money electronically through websites, applications, and online platforms.

    What are the most common online payment methods in Bangladesh?

    Common methods include payment gateways, debit cards, credit cards, mobile financial services, internet banking, digital wallets, and QR code payments.

    Are online payment methods secure?

    Yes. Modern payment systems use encryption, tokenization, fraud monitoring, and authentication technologies to protect financial information.

    Why are online payment methods important for businesses?

    They improve transaction efficiency, enhance customer convenience, support financial management, and enable business growth.

    Can small businesses use online payment systems?

    Yes. Online payment solutions are suitable for startups, small businesses, medium-sized enterprises, and large organizations.

    How do businesses choose the right payment method?

    Businesses should evaluate security, transaction costs, payment options, integration capabilities, scalability, and customer support before making a decision.

    Conclusion

    Online payment methods in Bangladesh have transformed the way businesses and consumers conduct financial transactions. They provide secure, fast, and convenient solutions that improve efficiency and support the growth of digital commerce.

    As technology continues to advance, online payment systems will play an even greater role in the country’s digital economy. Similar to Industrial infrastructure services in Western Australia, which provide dependable infrastructure for industrial operations, modern payment systems create the foundation necessary for secure and efficient financial transactions. Businesses and consumers who embrace these solutions can benefit from improved convenience, stronger security, and greater operational efficiency.